Jyoti CNC Automation vs Macpower CNC Machines: Two bakeries on one street. The bigger one is building an oven for plainer bread
Pranav Yadav · · 9 min read
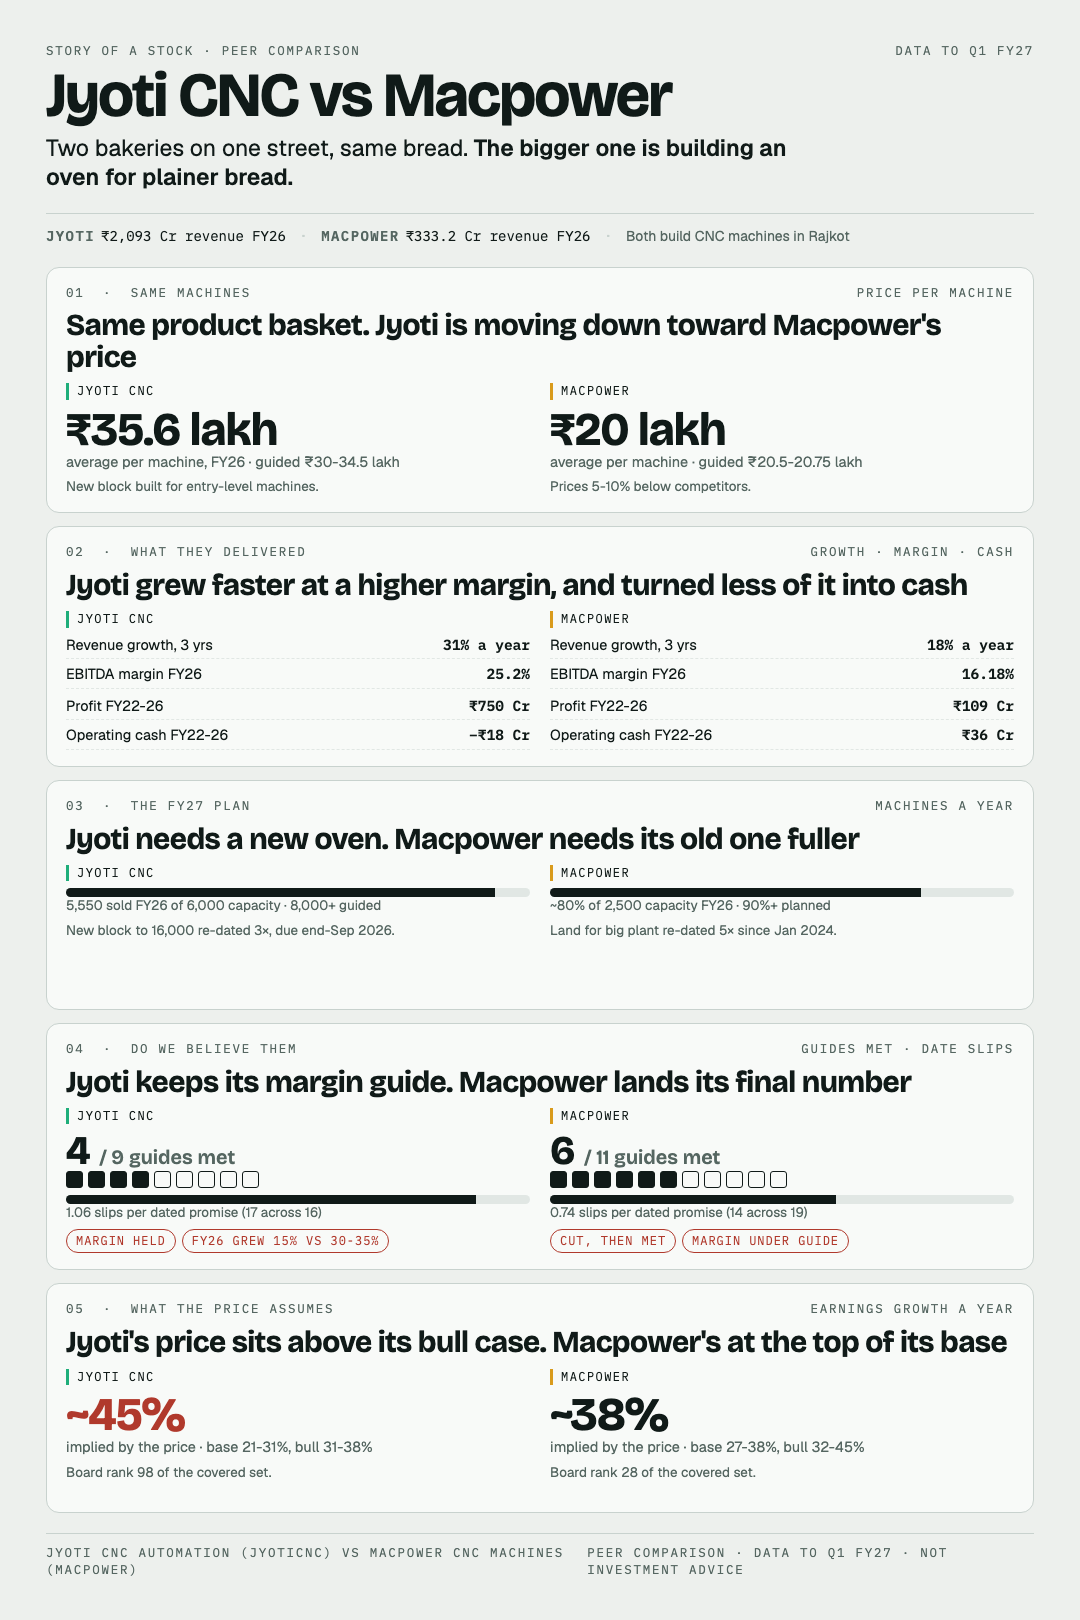
Both companies on one page. Below is the same thing in words, built from 23 earnings calls, 25 investor decks and four annual reports across the two companies, Q1 FY24 to Q1 FY27.
Picture two bakeries on the same street, baking the same bread for the same customers. A handful of others share the street, and together they bake nearly all the bread in town.
The street is Rajkot, and the bread is the CNC machine, the lathes and machining centres that engineering shops and defence plants use to cut metal. Jyoti CNC Automation and Macpower CNC Machines are two of the bakeries.
That is not my framing. On the Q1 FY26 call, an analyst asked Macpower's CMD how it differs from "Jyoti CNC or Lokesh Machines". His answer: "we all have a same product basket, same distribution network, same pattern, same working method."
I wrote about each on its own today: Jyoti as a machine that holds tolerance while its calendar drifts, Macpower as a restaurant with every table booked. Side by side, they say something neither post could.
The central takeaway
Jyoti has the better record on the two numbers most people check first: revenue growth of 31% a year over three years against Macpower's 18%, at a 25% EBITDA margin against 16%. Yet our own board ranks Jyoti 98th and Macpower 28th, and Jyoti's price asks for more.
On guidance both records are mixed, and each keeps a different promise. Jyoti keeps its margin guide. Macpower lands its final revenue number. Neither keeps a date.
The question is not which bakery is better. It is which risk you would rather own. Jyoti's risk is an oven that is not yet lit. Macpower's is an oven it must run hotter this year, and a second one it needs by next.
At a glance
- Size. FY26 revenue of ₹2,093 Cr at Jyoti and ₹333.2 Cr at Macpower. Market value of ₹23,879 Cr and ₹2,209 Cr.
- Price of a machine. About ₹35.6 lakh at Jyoti in FY26, now guided at ₹30-34.5 lakh. About ₹20 lakh at Macpower, guided at ₹20.5-20.75 lakh.
- Revenue growth, three years. 31% a year at Jyoti, 18% at Macpower.
- EBITDA margin, FY26. 25.2% at Jyoti, 16.18% at Macpower.
- Cash, FY22 to FY26. Jyoti reported ₹750 Cr of profit and operating cash that summed to minus ₹18 Cr. Macpower reported ₹109 Cr of profit and ₹36 Cr of operating cash.
- Guidance record. Jyoti met 4 of 9 closed financial guides, with 17 slips across 16 dated promises. Macpower met 6 of 11, with 14 slips across 19.
- What the price assumes. About 45% earnings growth a year at Jyoti and 38% at Macpower.
Where this lives on the portal: the Jyoti CNC Automation guidance page and the Macpower CNC Machines guidance page.
What you need to know first
The price of a CNC machine barely moves. Macpower's has sat near ₹20 lakh for two years, and Jyoti's is being guided down, not up. So revenue at both is a count of machines times a flat or falling price, and more machines means more floor space.
So almost every number below comes back to how full the oven is and when the next one opens. Both also bake long before anyone pays, which makes cash its own question.
1. They make the same machines, and Jyoti is moving down toward Macpower's price
Jyoti works higher up the range. Its average machine fetched ₹35.62 lakh in FY26, and it owns Huron, a French maker of 5-axis machines for aerospace. Macpower averages about ₹20 lakh and says it prices 5-10% below competitors.
The gap is narrowing from Jyoti's side. Its new Rajkot block is built for entry-level machines, and it now guides about ₹30-34.5 lakh a machine. More loaves, each plainer, is how 44% more machines become 25-30% more revenue in FY27.
Both are rated no moat, though only Macpower's rating has been through a downturn. That Jyoti is moving into Macpower's price band is the direction of a guide, not yet a result.
2. Jyoti grew faster at a higher margin, and turned even less of it into cash
Jyoti's revenue went from ₹929 Cr in FY23 to ₹2,093 Cr in FY26, partly a recovery after losses in FY22 and FY23. Macpower's went from ₹202 Cr to ₹333 Cr. Jyoti printed 27.0% and 25.2% EBITDA margins in FY25 and FY26, inside its guide. Macpower climbed from 10.24% to 16.18%, below every guide it gave.
Cash is where the better record stops. Over five years Jyoti's operating cash summed to minus ₹18 Cr against ₹750 Cr of profit. Macpower turned ₹109 Cr of profit into ₹36 Cr. On Screener's figures Jyoti held about 450 days of inventory in FY26 and Macpower about 260, and Macpower earns more on its capital, 29.1% against 21.3%.
So why does our board rank Jyoti 70 places lower? Of the 0.89 points between the composites, 0.68 comes from our read of each earnings call (7.62 against 6.67) and the growth score (7.2 against 6.6), and 0.20 from valuation. The gap is how the calls read, not what either company delivered.
3. FY27: Jyoti needs a new oven, and Macpower needs its old one fuller
Jyoti sold 5,550 machines in FY26 from a plant rated for 6,000. The FY27 guide of more than 8,000 only fits once the new block lifts capacity to 16,000. Demand is not the question: the ₹4,848 Cr order book is about 2.3 times FY26 revenue.
Macpower's plant reached 2,500 machines a year in November 2025 and ran about 80% full in FY26. The plan is 90%-plus, about ₹460 Cr at ₹20.5 lakh a machine, and the ₹456 Cr order book covers roughly a year of it. FY28's ₹600 Cr needs a new 13-acre site, due around June 2027.
Jyoti has the queue and waits on the oven. Macpower has the oven for this year and needs the queue to keep growing.
4. Both calendars slip, and Jyoti's biggest date is due this week
Jyoti's new block was first dated before March 2025, then December 2025, then June 2026, then end-September 2026. The Q1 FY27 deck still showed 6,000 machines installed. The Q2 call will say whether this date held.
Huron is a risk only Jyoti carries: a French investigation into suspected dual-use exports, ₹67 Cr of revenue reversed, and an auditor's going-concern emphasis.
Macpower's 60-acre plant has waited on land since a January 2024 MoU. The land was first due by December 2024 and has been re-dated five times; in July 2026 it was "15 days or a month" away.
Jyoti slips 1.06 times per dated promise, Macpower 0.74.
5. Each keeps a different promise: Jyoti the margin, Macpower the final number
Jyoti's margin guide held both years; its growth guides did not. In November 2025 the MD confirmed 30-35% growth for FY26, and FY26 grew 15.2%. Aerospace orders were guided at ₹1,500-2,000 Cr for FY25 and came in near ₹700 Cr.
Macpower runs the other way. FY25 was guided at 25-30% growth, cut in February 2025, and delivered 8.6%. FY26 started at ₹350-400 Cr, was cut to ₹300-330 Cr, and delivered ₹333.2 Cr. The first number runs high, the last lands close, and the margin comes in under the guide.
So on Jyoti, the margin guide has earned more weight than the growth guide. On Macpower, the last revenue number has earned more than the first. Both records are labelled mixed.
6. What the price already assumes
Working back from today's price, Jyoti needs about 45% earnings growth a year for two years. Our base case from its own guides is 21-31% and our bull case 31-38%, so the price sits above the top of the bull case. The conservative case is 3-16%.
Macpower needs about 38%. Our base case is 27-38% and our bull case 32-45%, so its price sits at the top of the base case.
Jyoti's price pays for the new oven lighting on time, filling, and Huron clearing. Macpower's pays for the old oven at 90% and a second one on time.
What would make me wrong
On Jyoti:
- The block produces from October as dated, and quarterly machine sales run well above 2,000 by the second half.
- The ₹67 Cr of Huron revenue is rebooked, which adds about three points to FY27 growth.
- Cash catches up. FY26 operating cash was ₹87 Cr before the Huron seizure.
On Macpower:
- The order book keeps growing 30%-plus and the rented sheds carry FY27 past ₹450 Cr.
- The 13-acre site opens early, and the land for the big plant finally arrives.
- The margin reaches the top of its FY27 band, near 18%.
The opposite error would be to read Jyoti's lower rank as a worse business, or Macpower's higher rank as a cleaner record.
The one question that matters
How many machines does each oven turn out in a quarter?
Jyoti's 6,000-a-year plant tops out near 1,500 a quarter, and Q1 FY27 shipped about 1,400. Macpower's 2,500-a-year plant tops out near 625, and FY27 needs about 560. Both FY27 plans are bets against those two ceilings.
What I'll be watching
- Does Jyoti's Q2 call report the new block producing, and a machine count above 1,500?
- Does Macpower's utilisation reach 90% on the Q2 and Q3 calls?
- Does either company's operating cash start to track its profit?
Final assessment
Same bread, same street. Jyoti bakes more, at a better margin, and waits on an oven due this week. Macpower bakes less, runs its oven hotter, and needs a second one by next year. Neither turns much of its bread into cash, and neither keeps a date.
The full reads are on the Jyoti CNC Automation page and the Macpower CNC Machines page.
The bigger bakery is building an oven for plainer bread. The smaller one already bakes it, and the price asks more of the one still waiting on its oven.
This is a summary of what Jyoti CNC Automation's and Macpower CNC Machines' filings and earnings calls say. It is not investment advice or research.