Macpower CNC Machines: Every table is booked. The bigger hall is still on paper
Pranav Yadav · · 7 min read
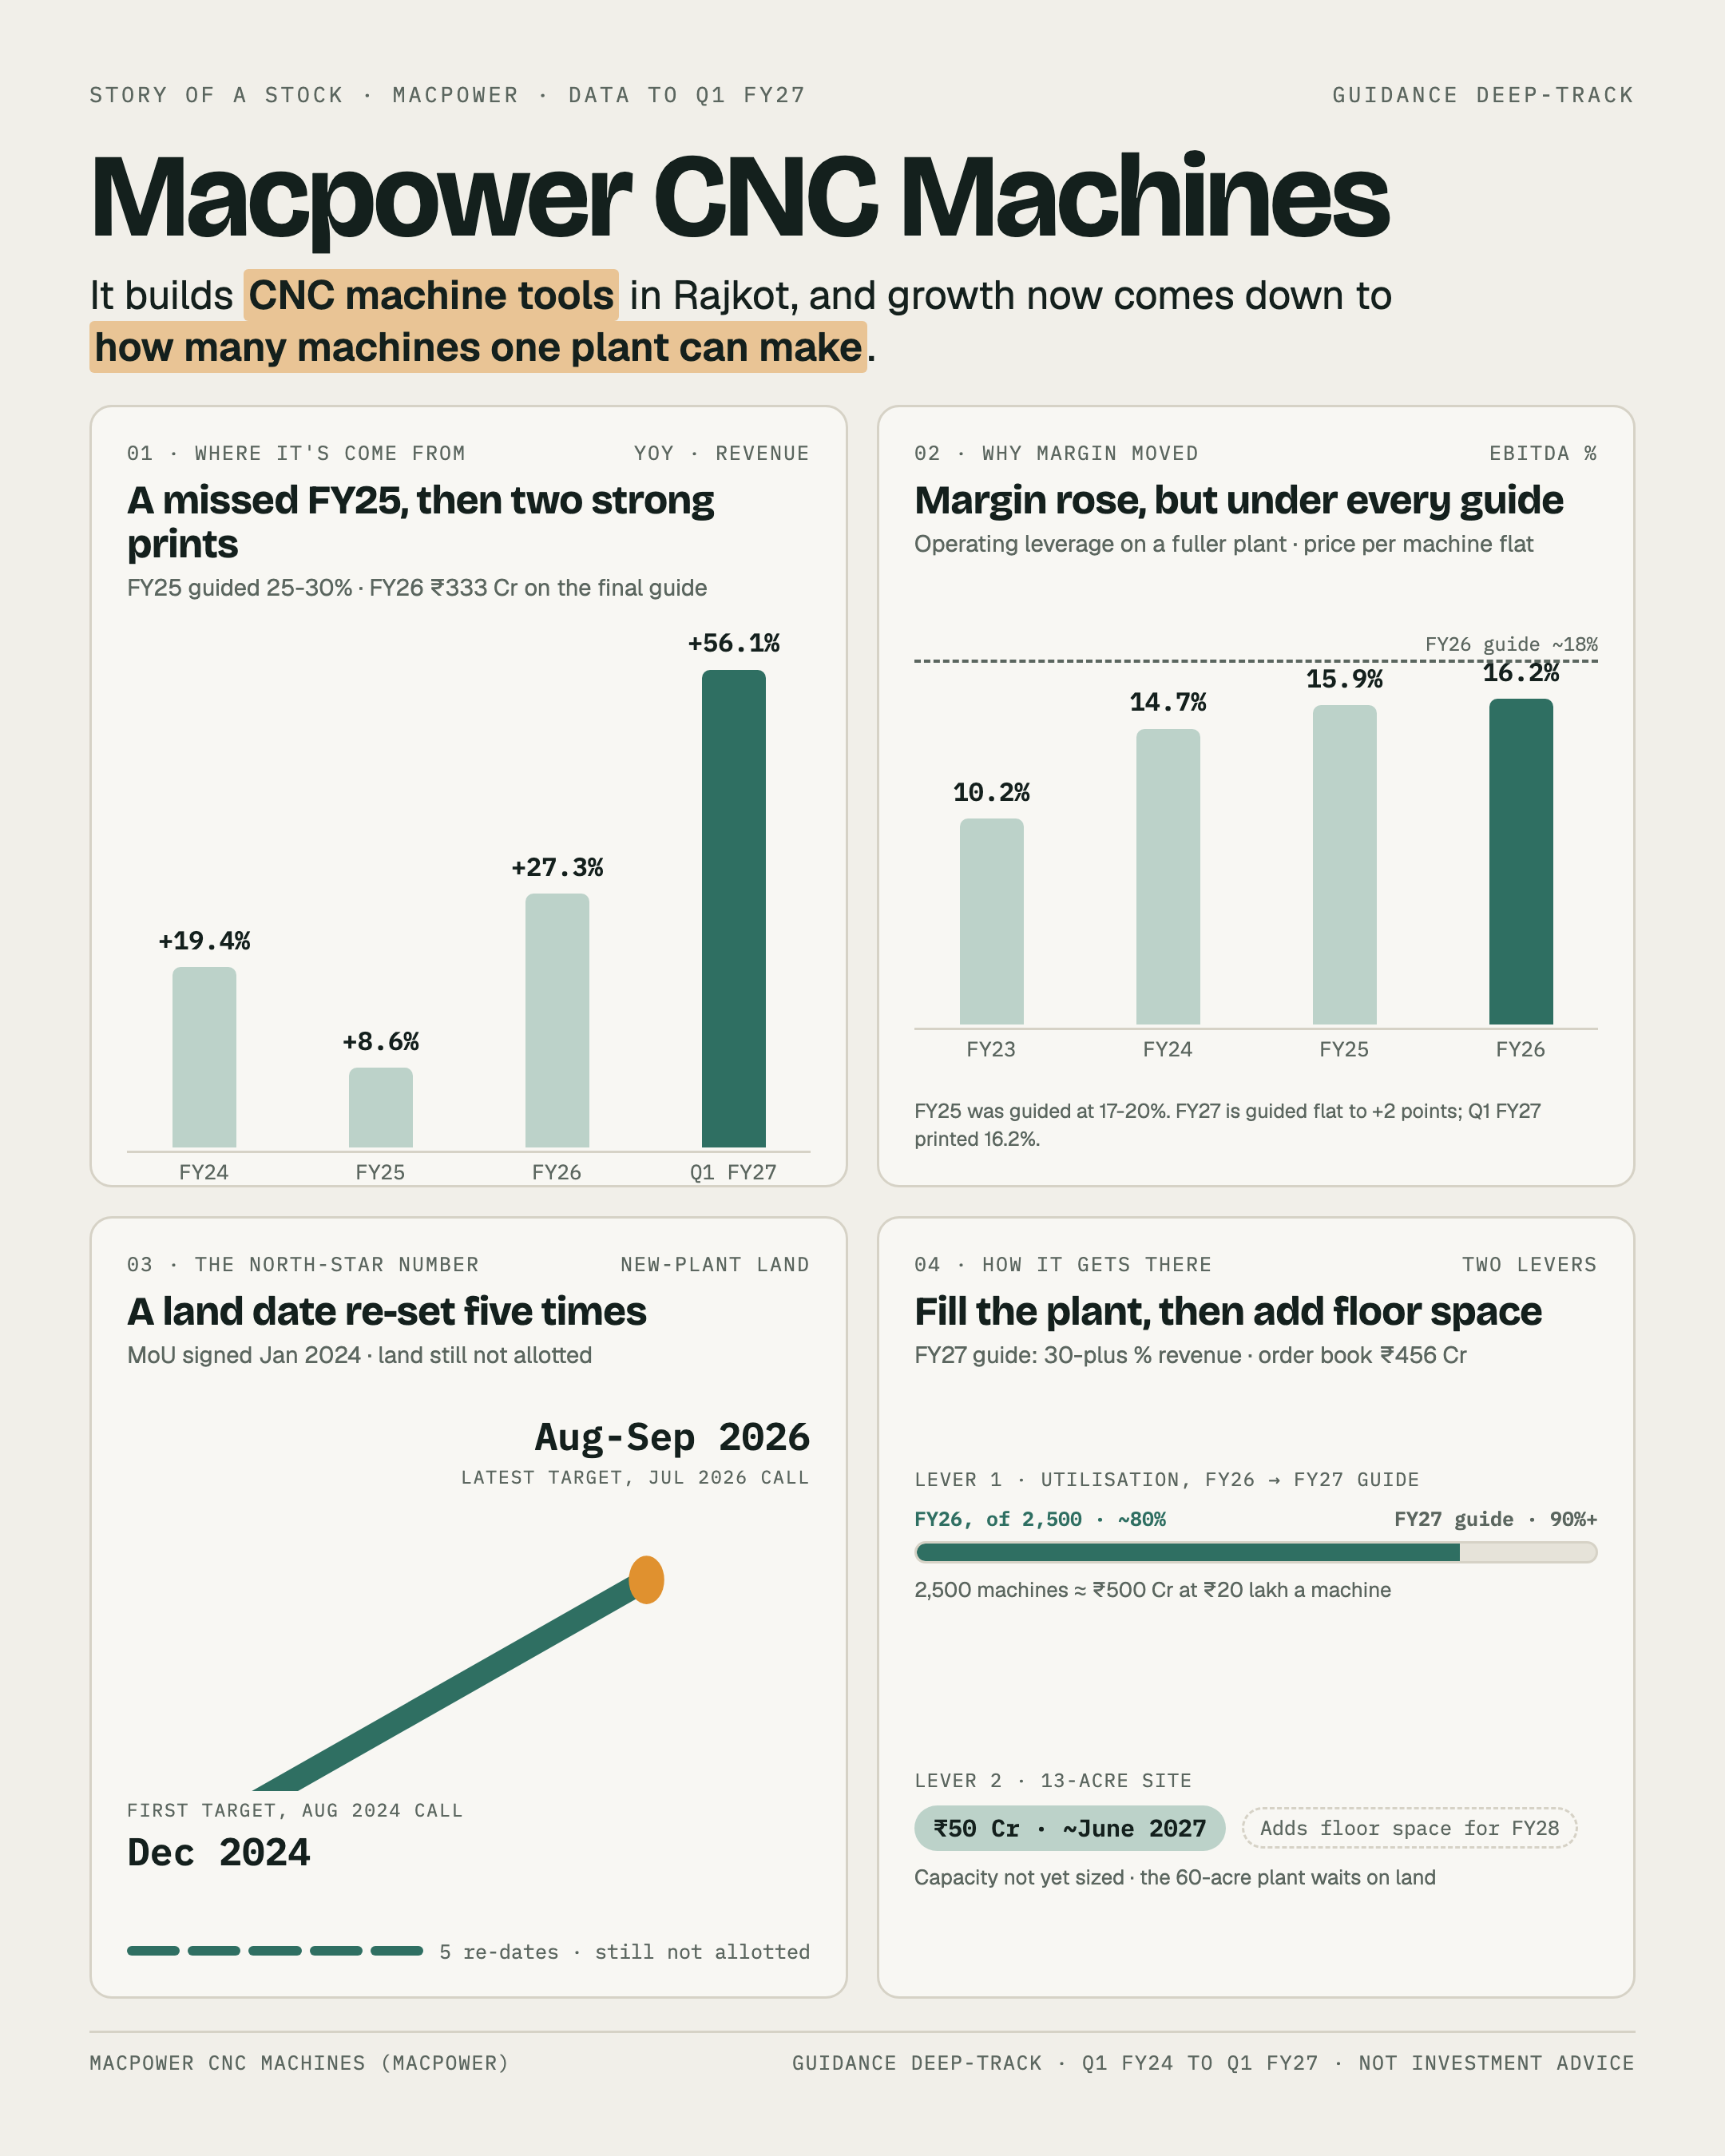
That's the Macpower story on one page. Below is the same thing in words, built from twelve earnings calls and thirteen investor decks, Q1 FY24 to Q1 FY27, and the FY26 annual report.
Picture a restaurant where every table is booked for weeks. The menu is the same as the six other places on the street, and the price of a plate has not moved in two years. The only way to take more money is to serve more covers: fill every table, then open a new room.
Macpower CNC Machines is that restaurant. It builds CNC lathes and machining centres in Rajkot and sells them to small engineering shops, auto suppliers and a few defence buyers. Orders are coming in faster than the plant can build. The price of a machine sits near ₹20 lakh.
The owner has also been promising a banquet hall. The land for it was first due by December 2024. It has been re-dated five times since, and it has still not arrived.
The central takeaway
The record is mixed. Management met 6 of the 11 financial guides that have closed, and its dates slipped 14 times across 19 dated promises. FY25 was a bad miss. FY26 landed, but only on a guide that had been cut first.
The debate is no longer whether demand is there. It is whether one full plant, then a second smaller site, can carry 30% a year while the big plant waits for land.
At a glance
- FY26 delivered: revenue of ₹333.2 Cr, up 27.3%, after 8.6% in FY25 and 19.4% in FY24.
- The latest quarter: Q1 FY27 revenue of ₹95.24 Cr, up 56.1% on a weak Q1 FY26.
- The FY27 guide: revenue growth raised from 25-30% to 28-30%, then to "30-plus" in July 2026.
- Orders: a ₹456 Cr order book in June 2026, up 32% on the year.
- The ceiling: 2,500 machines a year, which management puts at about ₹500 Cr of sales.
- Margin: EBITDA margin of 16.18% in FY26, below the roughly 18% guided for the year.
Where this lives on the portal: the Macpower CNC Machines guidance page.
1. The revenue record is one bad year and one year met after a cut
In October 2023 management guided FY25 revenue growth of at least 25-30%. It restated some version of that for over a year, then cut it in February 2025 to "above the double digit". FY25 closed at ₹261.8 Cr, up 8.6%. That misses even the lowered bar.
FY26 started with a ₹350-400 Cr target in February 2025. By August it had become ₹300-350 Cr, and in November it was 25-30% growth and a close of ₹300-330 Cr. FY26 delivered ₹333.2 Cr, up 27.3%, which meets the last guide and misses the first.
So the pattern is not a company that never delivers. It is a company whose first number is usually too high, and whose last number is usually close.
2. The price of a machine has not moved, so growth is a count of machines
Average realisation was about ₹25 lakh in the FY26 guide. It came in near ₹20 lakh, and the FY27 guide is ₹20.5-20.75 lakh after a February hope of 10-20% more was dropped. The higher-end NEXA range is now about 40% of the order book, and the CMD said plainly that it will not lift the average.
That fits the moat read, which is now no moat. The CMD's own description of the business was "same product basket, same distribution network, same pattern, same working method" as its rivals, and management says it sells 5-10% below competitors. Same menu, same prices as the rest of the street.
The evidence here is strong. Growth at Macpower is a volume story, and volume is capped by floor space.
3. FY27 is a plan to fill the existing plant, and the orders cover it
Capacity reached 2,500 machines a year in November 2025, about three quarters later than first promised. FY26 ran at around 80%. The FY27 plan is 90%-plus, helped by three rented sheds.
The arithmetic holds. At 90% of 2,500 machines and ₹20.5 lakh each, the plant makes about ₹460 Cr. The CMD's own path is ₹450 Cr this year and ₹600 Cr next. With a ₹456 Cr order book, and ₹145 Cr of new orders against ₹95 Cr shipped in Q1, the tables for FY27 are booked.
This is the best-evidenced thread in the book. FY27 depends on execution in a known building, not on anything new.
4. Margins rose on a fuller plant but stayed under every guide
EBITDA margin went from 10.24% in FY23 to 16.18% in FY26. The CMD credits operating leverage: a fuller room spreads the rent. But FY25 was guided at 17-20% and delivered 15.87%, and FY26 was guided at about 18% and delivered 16.18%.
For FY27 the guide is modest: hold the margin, or add one to two points. Q1 printed 16.20%. The 25% figure that appears in the decks is tied to the 60-acre plant, and the latest call capped the near-term target at 20-21%.
Cash is the weaker part of the same picture. Over FY22-FY26 the company reported ₹109 Cr of profit but ₹36 Cr of operating cash, mostly because inventory was built up ahead of the order book.
5. The big plant has waited on land for two years, the hall still on paper
The 60-acre plant was announced with a Gujarat MoU in January 2024. The land was first due by December 2024, then March-April 2025, then mid-2025, then December, then March 2026, and in July 2026 it was "15 days or a month" away. Phase-one cost rose from ₹30-40 Cr to about ₹125 Cr including land on the way.
In the meantime the company leased a 13-acre site next door. It is budgeted at about ₹50 Cr, with a 25% state capital subsidy, and should be in use around June 2027. Its capacity has not been sized yet.
That matters because FY28's ₹600 Cr is about ₹100 Cr more than the existing plant can make. FY27 needs a full room. FY28 needs the new room to open on time.
6. What the price already assumes
The price implies about 38% earnings growth a year over the next two years. Our base case runs 27-38% and our bull case 32-45%, so the price sits at the top of the base case and near the middle of the bull case.
In words: the market is paying for FY27 landing and for the 13-acre site delivering FY28 on schedule, from a company whose first guides have usually been too high.
What would make me wrong
- The order book keeps growing at 30%-plus and the rented sheds let FY27 clear ₹450 Cr with room to spare.
- The 13-acre site opens early, and the land for the big plant finally arrives in the promised month.
- Margin reaches the top of the FY27 band, near 18%, and operating cash starts to track profit.
The opposite error would be to treat the FY25 miss as the pattern, when FY26 already met its final guide.
The one question that matters
Can the plant run at 90%? It ran at about 80% in FY26. Management says 90%-plus for FY27, and that one number decides whether 30% is a plan or a hope.
What I'll be watching
- The utilisation figure on the Q2 and Q3 FY27 calls.
- Whether the land letter for the 60-acre plant actually arrives.
- The margin and FY28 guide the CMD has promised for the Q3 call.
Final assessment
Macpower has the orders. What it has not shown is that it can build much faster than it books, or that its dates hold.
The full read, with every guide and its trail, is on the Macpower CNC Machines company page.
Every table is booked for this year. Next year's covers depend on a room that is still being built, and the big hall has been one month away for two years.
This is a summary of what Macpower CNC Machines's filings and earnings calls say. It is not investment advice or research.