Jyoti CNC Automation: Its machines hold tolerance. Its calendar does not
Pranav Yadav · · 6 min read
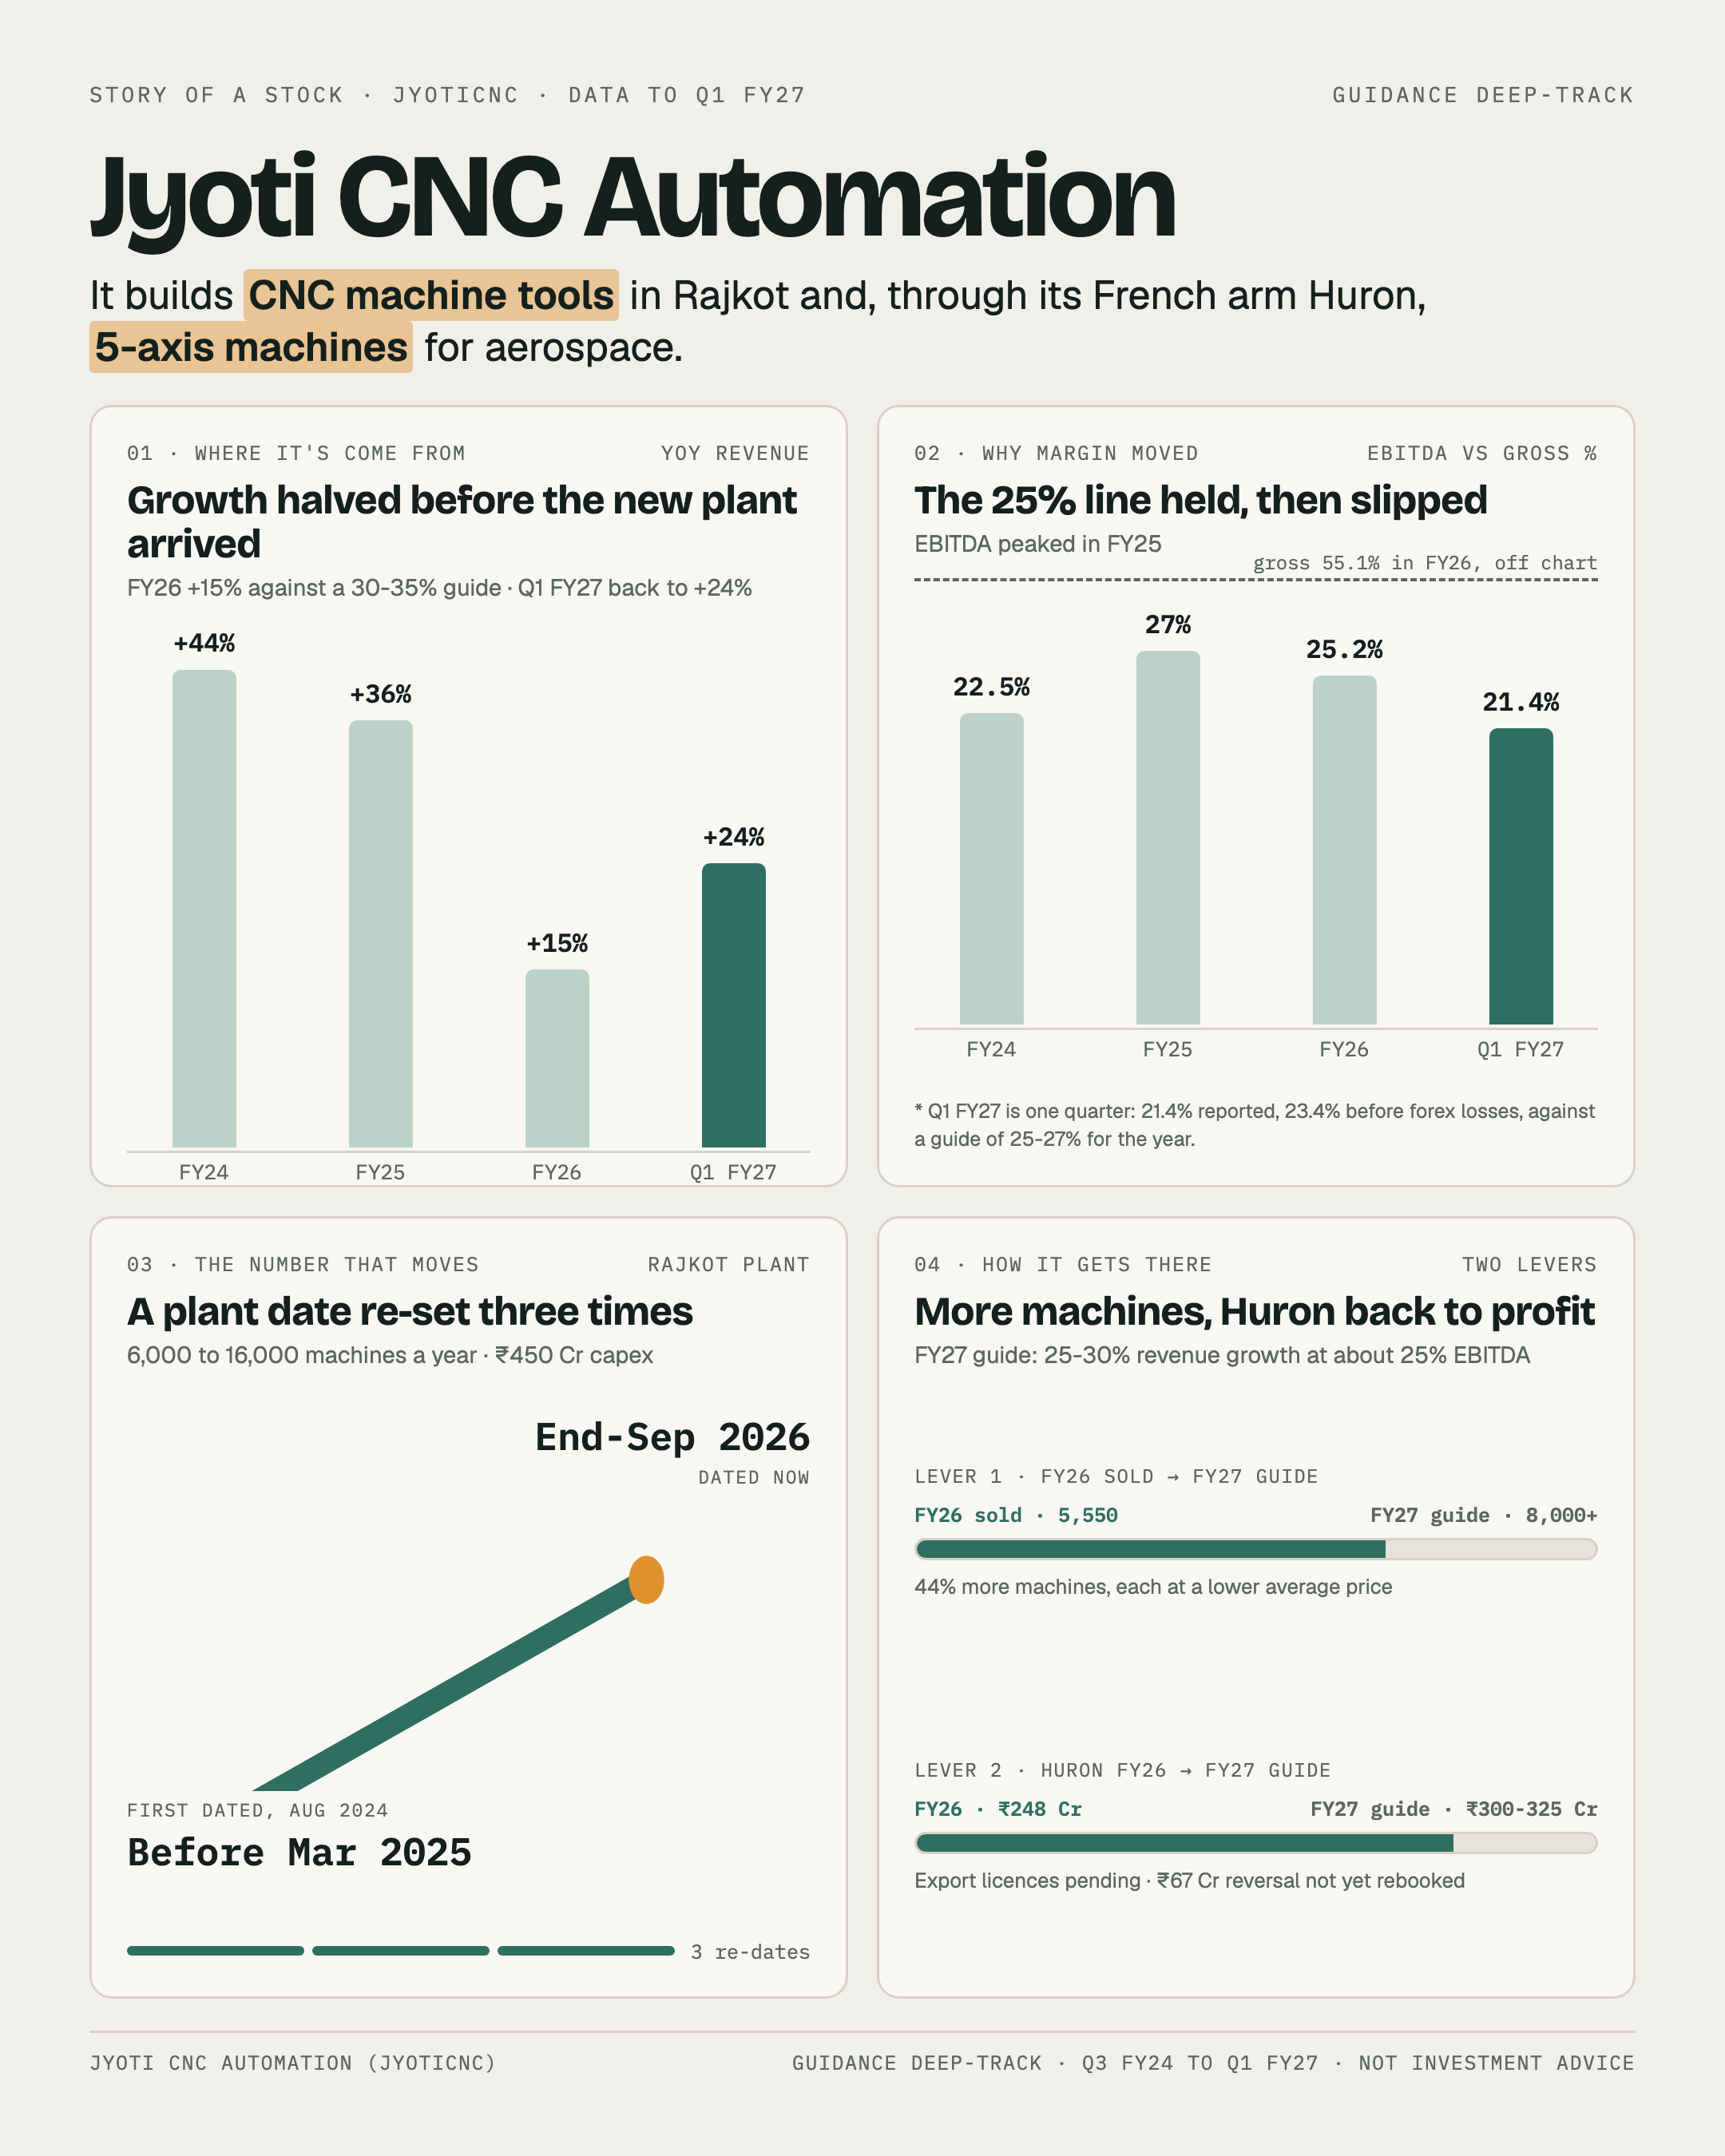
That's the Jyoti CNC story on one page. Below is the same thing in words, built from eleven earnings calls and twelve investor decks, Q3 FY24 to Q1 FY27, and the FY24 to FY26 annual reports.
A CNC machine is sold on one promise: tolerance. Cut a thousand parts and every one lands within a few microns of the drawing. A buyer does not care how fast the spindle turns if the part drifts.
Jyoti CNC Automation sells that promise. It builds CNC lathes and machining centres in Rajkot, and through its French arm Huron it builds 5-axis machines for aerospace. Its customers run to HAL, Airbus and a long list of auto and engineering shops.
Hold the company's own guidance to the same standard and the result splits in two. The margin guide has held within tolerance. The growth guides and the dates have not.
The central takeaway
The record is mixed. Management met 4 of the 9 financial guides that have closed, and its dates slipped 17 times across 16 dated promises. The two margin guides landed. Revenue, aerospace orders and Huron all missed by wide gaps.
The debate is no longer whether demand is there, because the order book covers it. It is whether the new plant arrives and fills faster than each machine gets cheaper.
At a glance
- FY26 delivered: revenue of ₹2,093 Cr, up 15.2%, or about 19% before a ₹67 Cr Huron reversal.
- The guide it missed: in November 2025 the MD confirmed 30-35% growth for FY26.
- Margin: EBITDA margin of 27.0% in FY25 and 25.2% in FY26, inside the guide; Q1 FY27 printed 21.4%.
- Orders: a ₹4,848 Cr order book at 30 June 2026, about 2.3 times FY26 revenue.
- The plant: 6,000 machines a year today, 16,000 once the new block opens, now dated end-September 2026.
- The FY27 guide: 25-30% revenue growth on more than 8,000 machines, against 5,550 sold in FY26.
Where this lives on the portal: the Jyoti CNC Automation guidance page.
1. The margin guide is the one promise that held within tolerance
Management has guided an EBITDA margin of about 25%, in a 25-27% range, since May 2024. FY25 delivered 27.0%, at the top of the band. FY26 delivered 25.2%, a fraction above the floor, even with the Huron reversal inside the year.
Q1 FY27 is the first crack. The reported margin was 21.4%, or 23.4% before forex losses, against a floor the MD restated on the same call. One quarter is not a year, and the second half is where this company books most of its sales.
So the evidence is good but not closed. This is the part of the machine that has held its setting.
2. Growth missed wide twice, and the high-value legs missed wider
In August 2024 the MD answered a question on FY25 guidance by pointing to Q1's 74% pace. By February 2025 he said no revenue guidance had been given. FY25 grew 36% to ₹1,818 Cr. I do not score that one, because management disowned it, but the gap is worth knowing.
FY26 is harder to set aside. In November 2025 the MD set out 30-35% growth for the next three to four years and said "Correct. Absolutely." when asked if FY26 would grow at that rate. FY26 grew 15.2%. By February 2026 the multi-year frame had become 25-30%.
The aerospace and Huron guides missed by more. Aerospace and defence orders were guided at ₹1,500-2,000 Cr for FY25 and came in near ₹700 Cr. Huron was guided at €50-55 million of FY25 revenue and delivered about ₹253 Cr, roughly €27 million.
3. The new Rajkot plant has been re-dated three times, and FY27 rides on it
The expansion adds 10,000 machines a year to a plant that makes 6,000, for about ₹450 Cr. It was first dated before March 2025. It then moved to FY26 or December 2025, then June 2026, then end-September 2026. The Q1 FY27 deck still shows 6,000 machines installed.
FY27 needs it. The guide is more than 8,000 machines, up 44% on 5,550, and the new block is built for entry-level machines. Average realisation was ₹35.62 lakh a machine in FY26, and management now guides about ₹30-34.5 lakh. More machines, each at a lower price, is how 44% volume becomes 25-30% revenue.
The orders are real: ₹4,848 Cr covers more than two years of sales. What is loose is the calendar, the tolerance this section is about.
4. Huron is the part the documents cannot yet close
Huron's new French plant was first dated September 2024 and opened on 19 November 2025, four slips later. FY26 revenue was ₹248 Cr against about ₹253 Cr the year before, when management had guided about 1.5 times. The FY27 guide was ₹300-350 Cr in May 2026 and ₹300-325 Cr in August, at an 8-10% EBITDA margin, down from the 20%-plus first promised.
Then there is the investigation. French authorities opened a judicial investigation into suspected dual-use exports. €3.02 million of Huron's cash is seized, ₹67 Cr of revenue was reversed in Q4 FY26, and none of it had been rebooked by the August call. The auditor added an emphasis of matter on Huron's going concern in the FY26 annual report.
None of that makes Huron's future a miss. It makes it unknowable from the filings today.
5. What the price already assumes
The price implies about 45% earnings growth a year over the next two years. Our base case runs 21-31% and our bull case 31-38%, so the price sits above the top of the bull case. Our bear case is 3-16%.
In words: the market is paying for the plant arriving on its latest date, the machines filling it, the margin holding at 25%, and Huron's licences clearing. That is four promises from a company whose dates have slipped more often than they have held.
What would make me wrong
- The Rajkot block starts in October as dated, and quarterly machine sales run well above 2,000 by the second half.
- The ₹67 Cr is rebooked once licences clear, which adds about three points to FY27 growth.
- EMS orders convert. None had by August 2026, but management says 200 of its people are working with those customers.
The opposite error would be to read the margin record as the whole record, when growth and dates are where the misses sit.
The one question that matters
When does the new plant produce? It was first due before March 2025 and is now dated end-September 2026. Every FY27 number sits on that date.
What I'll be watching
- Machines sold in Q2 and Q3 FY27, against a run-rate of about 1,400 in Q1.
- Whether the Q2 call reports the new block producing, and the foundry that slipped to October.
- Any word on the French investigation and the ₹67 Cr of Huron revenue.
Final assessment
Jyoti has the orders and a margin that has held. What it has not shown is that it can hit a date, and FY27 is built on one.
The full read, with every guide and its trail, is on the Jyoti CNC Automation company page.
The machines hold a few microns. The calendar has drifted by eighteen months, and the price is set as if it had not.
This is a summary of what Jyoti CNC Automation's filings and earnings calls say. It is not investment advice or research.