Laurus Labs: It is building the kitchen Neuland already runs. Neuland's runs on five chefs
Pranav Yadav · · 8 min read
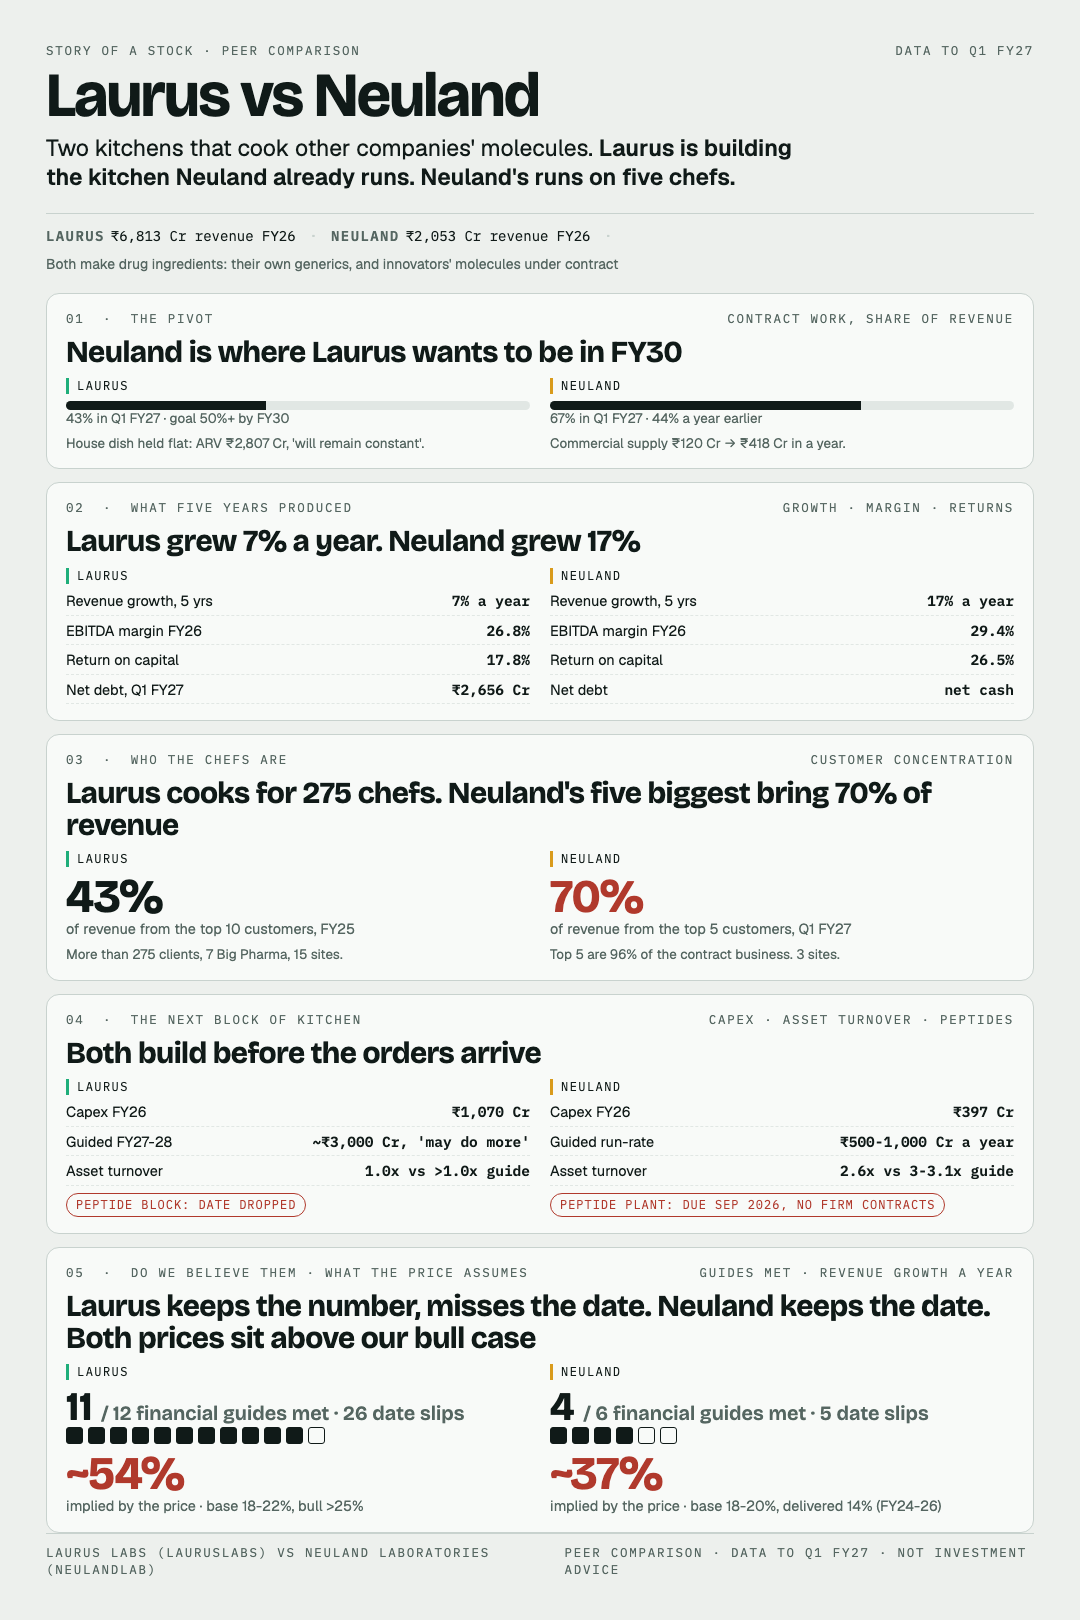
Both companies on one page. The same thing in words, built from 25 earnings calls, 27 investor decks and the broker notes, Q1 FY24 to Q1 FY27.
A kitchen can serve its own dish, or cook other chefs' recipes. When I wrote about Laurus Labs nine days ago, that was the whole story: a house dish, anti-retroviral medicine, that has stopped growing, and a rented kitchen, contract manufacturing for drug innovators, that has not.
Neuland Laboratories made that switch already: 67% of its Q1 FY27 revenue came from other companies' molecules. I read its guidance record two weeks ago, and in June I traced its 13x to exactly this shift.
The central takeaway
Neuland is already where Laurus says it will be in FY30: contract work is 67% of its revenue against 43%, reached on 17% a year of revenue growth over five years to Laurus's 7%. Yet Laurus is four times the market value, met 11 of 12 closed financial guides, and its price asks for more.
The two records are mirror images. Laurus lands its numbers and misses its dates. Neuland keeps its dates and missed one year's numbers.
The question is not which is the better contract manufacturer. It is which risk you would rather own. Laurus's risk is a kitchen being built ahead of its orders, on a calendar that slips. Neuland's is a kitchen already full, where five chefs bring 70% of the revenue.
At a glance
- Size. FY26 revenue of ₹6,813 Cr at Laurus and ₹2,053 Cr at Neuland. Market value of ₹1,08,966 Cr and ₹27,452 Cr.
- Contract work's share of revenue, Q1 FY27. 43% at Laurus, with a goal of at least half by FY30. 67% at Neuland, up from 44% a year earlier.
- Customer concentration. Laurus's top 10 customers were 43% of revenue in FY25. Neuland's top 5 are 70% and its top 10 are 77%.
- Guidance record. Laurus met 11 of 12 closed financial guides, with 26 slips across 11 of 14 dated projects. Neuland met 4 of 6, with 5 slips across 23.
- What the price assumes. About 54% revenue growth a year at Laurus and about 37% at Neuland, at flat margins. Our base cases are 18-22% and 18-20%.
Where this lives on the portal: the Laurus Labs guidance page and the Neuland Laboratories guidance page.
What you need to know first
Both companies make the active ingredient, the chemistry inside a pill, and supply it two ways: their own generic molecules, and molecules that belong to an innovator, made under contract. That second business is the same kitchen, rented to other chefs. Neither gives a revenue number, so the numbers below are about how much of the kitchen cooks for other chefs, and what the next block of kitchen costs.
1. Neuland is where Laurus wants to be in FY30
Laurus's contract work was 22% of revenue in FY24, 31% in FY26 and 43% in Q1 FY27, when it brought in ₹870 Cr, up 67% on a year earlier. Management wants at least half by FY30. The house dish is held flat on purpose: ARV revenue was ₹2,807 Cr in FY26, and management says the ₹2,800 Cr "will remain constant".
Neuland's contract work went from 44% of revenue in Q1 FY26 to 67% in Q1 FY27, and commercial supply did it: ₹120 Cr became ₹418 Cr in a year. Its generic leg is smaller, and one line is stuck. Paliperidone shipments have been held up since Q3 FY26.
It also got there faster: 17% a year of revenue growth over five years to Laurus's 7%, with FY25 the dip, down 4.7%, and FY26 the recovery, up 37%. Laurus's FY24 fell 17% when a ₹1,424 Cr one-off FY23 order dropped out.
2. Laurus cooks for 275 chefs. Neuland's five biggest bring 70% of the revenue
This is what size buys. Laurus serves more than 275 clients, seven of them Big Pharma, from 15 sites with 8,300 kL of capacity. Its top 10 customers were 43% of revenue in FY25.
Neuland runs three sites with 1,226 kL. Its top five customers are 70% of revenue, its top 10 are 77%, and within the contract business the top five are 96%. That is a full kitchen with a short guest list, and it explains the lumpiness: quarterly contract revenue ran ₹132 Cr in Q1 FY26 and ₹536 Cr in Q4 FY26.
I rate Neuland's moat narrow, on 18 clean USFDA inspections and the lock-in of exclusive innovator molecules, and Laurus's at none, because management itself says "nobody is going to use only one supplier". Neuland's narrow moat rests on five customers.
3. Both are building the next block of kitchen before the orders arrive
Laurus's FY26 capex was ₹1,070 Cr. The guide for FY27 and FY28 is about ₹3,000 Cr, reopened a quarter later with "we may do more than that", and Q1 FY27 capex alone was 19% of sales. Five years of building have left net debt at ₹2,656 Cr. The peptide block was dated for 2026, then Q2 FY27, and the Q1 FY27 deck carries no date, "based on customer demand".
Neuland's capex was ₹100-120 Cr a year when the window opened, ₹397 Cr in FY26, and the forward frame is ₹500-1,000 Cr a year. FY26's spend ran past operating cash, breaching its own rule that capex stays under 60% of it. The peptide plant, ₹254 Cr to take reactor capacity from 0.5 KL to 6.37 KL, was "ready by July, no change in the date" in May and "commissioned next month" in August. Management would not "go as far as to say that we have firm contracts".
Laurus is waiting for demand before it dates the block. Neuland built the block and is waiting for demand.
4. Laurus keeps the number and misses the date. Neuland keeps the date and missed the year
Of 12 closed financial guides, Laurus met 11. Of 14 dated projects, 11 slipped, 26 times; the gene and ADC facility alone moved from March 2026 to the end of 2027. The one margin guide that would have missed, 28-29% for FY25, was cut to "around 20%" more than a year before the year closed, and 20.1% was scored as met.
Of six closed financial guides, Neuland met four. Both misses are FY25: revenue guided "relatively flat" fell 4.7%, and a margin guided as "a slight drop" fell 730 basis points. Both guides had already been cut once. Of 23 dated commitments, five slipped, once each, the peptide plant among them.
Our scorer labels Laurus mixed and Neuland credible. Read the labels with the samples: Laurus has twice the closed guides and three times the dated projects.
5. What the price already assumes
At ₹2,011, Laurus's price needs about 54% revenue growth a year, with margins held flat. My base case is 18-22%, my bull case above 25%, and the company delivered 7% a year over five years. The price sits at about twice the bull case.
At ₹21,411, Neuland's price needs about 37%. The peptide post said 38.7%; the difference is the 28 September re-pricing. Management's own long-run aspiration is 18-20%, my base case is the same, and the delivered FY24 to FY26 rate was 14.3%.
Two cautions. Neuland's 55 times trailing earnings carries a quarter that grew 116%, so it flatters. Laurus's 54% is solved on a year in which margins stepped up, so it overstates the growth needed if the new margin holds.
Our board cannot split them. Laurus ranks 85th and Neuland 79th, on composites of 6.14 and 6.18. Laurus reads better on its calls and on growth; the whole of Neuland's lead is its price asking for less.
What would make me wrong
On Laurus:
- ₹870 Cr is the new floor. Contract revenue rose 48% on the previous quarter. If it holds, half of revenue arrives well before FY30.
- Margins keep rising. 31.8% in Q1 FY27 against 26.8% for FY26 means less growth is needed.
- The calendar stops mattering. A block that opens late but full still earns.
On Neuland:
- A first peptide contract is signed around commissioning, and the block with no orders gets one.
- Concentration is depth. Five innovators on exclusive molecules can be a stronger book than 275 clients who dual-source.
- FY27 and FY28 grow at about 20%, as management said in August, and 14.3% was the dip, not the trend.
The opposite error would be to read Neuland's credible label as safety, when its live book rests mostly on management's word and five customers, or to read Laurus's slips as failure, when every number it gave was met.
The one question that matters
How much revenue does each rupee of plant produce, and does it hold while both build?
Both guide this number and both are below their own guide. Laurus was meant to return to 1.1x within three years and prints 1.0x, with the goal now "above 1.0x, medium-term". Neuland called 3-3.1x optimised and prints 2.6x. The one that moves toward its guide while the plant grows is the kitchen that is filling.
What I'll be watching
- Does Neuland's Q2 FY27 call report the peptide plant commissioned, and a first contract with it?
- Does Laurus's contract revenue hold near ₹870 Cr, and does the fermentation site start by the third quarter of FY27?
- Does either asset turnover move toward its guide by the end of FY27?
Final assessment
Laurus is halfway through a switch Neuland finished. Its numbers land, its dates do not, and its price assumes the switch is done. Neuland's kitchen is full and about to get a new block, with five chefs at the pass and no order yet for the new counter.
The full reads are on the Laurus Labs page and the Neuland Laboratories page.
One kitchen is being built for chefs who have not yet booked. The other is booked solid by five. Each price assumes the booking holds.
This is a summary of what Laurus Labs' and Neuland Laboratories' filings and earnings calls say. It is not investment advice or research.