Aeroflex Industries: The pipe-fitter found one big contractor, and now works to the contractor's clock
Pranav Yadav · · 7 min read
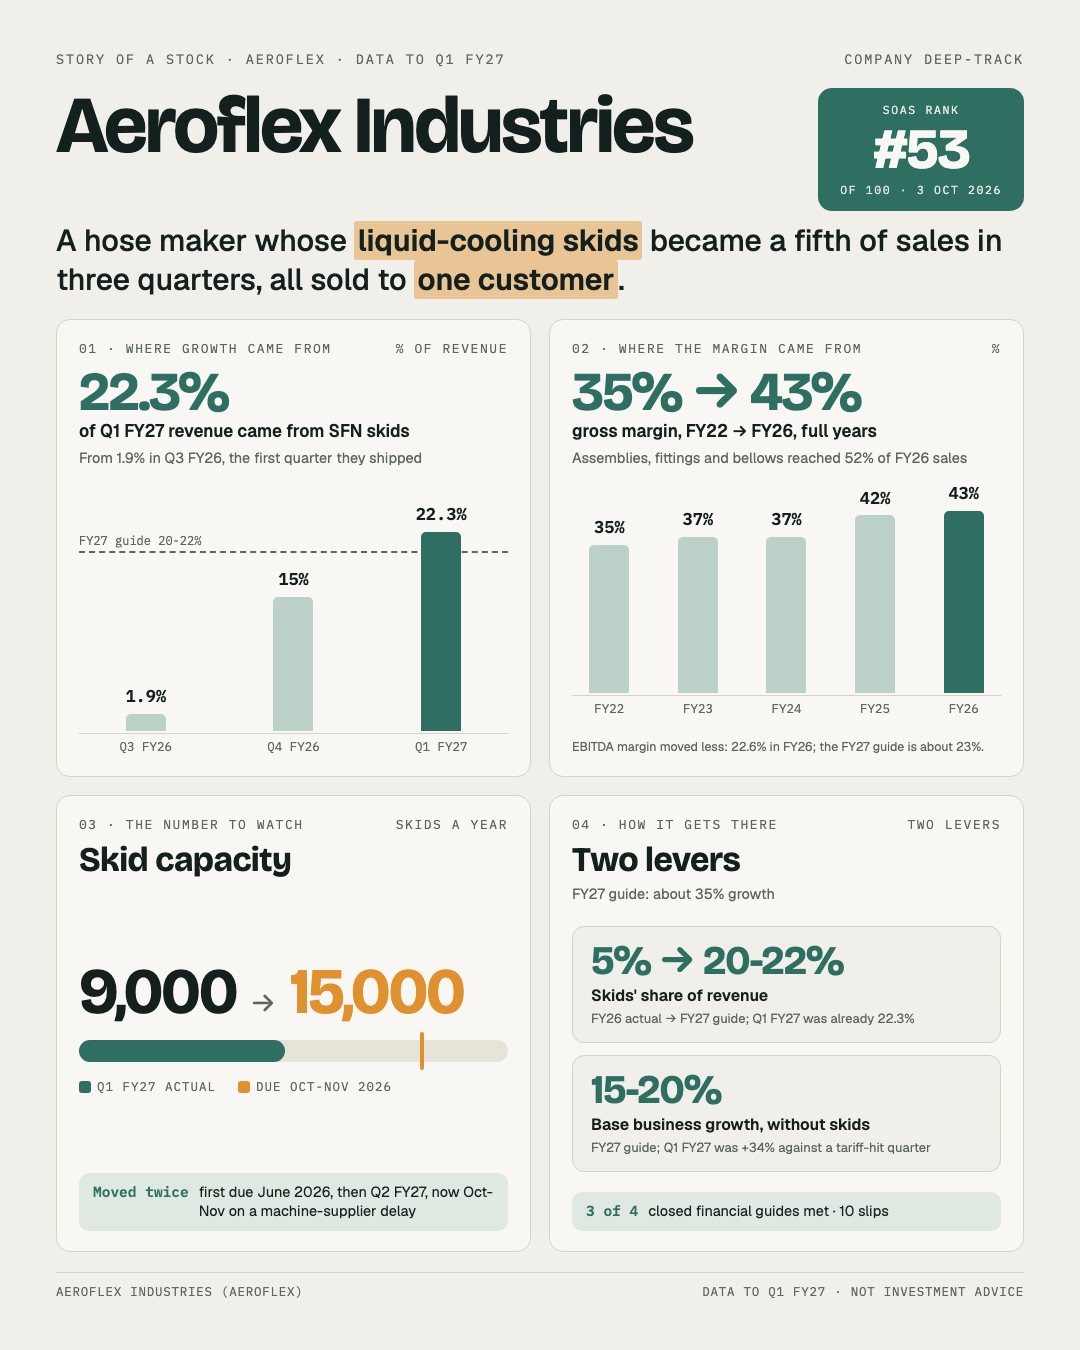
That's the Aeroflex Industries story on one page. Below is the same story in words, built from twelve quarters of earnings calls and investor decks, two annual reports and five broker notes.
My last post on Aeroflex said its growth story was 15,000 skids it hadn't finished building. That still holds, with one correction: the finish date has moved twice, not three times. This time I also read every section against the annual reports.
Picture a pipe-fitter. For years he made steel hose and fitted it into assemblies for factories, shipyards and refineries, mostly abroad. Then one large contractor building data centres asked him to plumb its cooling systems, and signed him up for five years.
That contractor now buys a fifth of what he makes. Aeroflex is the pipe-fitter, and the cooling work runs at the contractor's pace and the pace of the fitter's own new tools.
The central takeaway
The record is mixed. Aeroflex has met 3 of its 4 closed financial guides, and its dates slip: 10 slips across 6 of 16 dated commitments.
The debate is no longer whether the liquid-cooling business is real. It is whether one contractor, and one line that keeps moving its finish date, can carry a price that assumes more than our best case.
At a glance
- What it sells: in Q1 FY27, flexible hoses were 37% of revenue, assemblies and other products 41%, and liquid-cooling skids 23%. Exports were 58%.
- The new line: skids went from 1.9% of revenue in Q3 FY26 to 22.3% in Q1 FY27, all sold to one buyer.
- The FY27 guide: about 35% growth, with the base business at 15-20% and skids at 20-22% of revenue.
- The line behind it: skid capacity is 9,000 a year; 15,000 is now due in October-November 2026, after first being promised for June.
- Returns: return on capital fell from 36% in FY22 to 19% in FY26.
- What the price assumes: about 54.5% earnings growth a year, at ₹521 on 1 October.
Where this lives on the portal: the Aeroflex Industries guidance page.
1. Aeroflex earns more the more of its hose it fits, and that mix lifted gross margin from 35% to 43%
Bare hose is the commodity end of the trade. Management puts its EBITDA margin at 16-20%, against 22-26% once the same hose is built into an assembly with fittings.
Over five years the fitting work grew. Assemblies, fittings and bellows reached 52% of FY26 sales, and gross margin rose from 35% in FY22 to 43% in FY26. That is the pipe-fitter charging for labour, not just pipe.
The work is still mostly abroad, at 58% of Q1 FY27 sales, and one export customer alone takes about 25-26% of the company's sales.
2. Skids went from 1.9% to 22.3% of revenue in three quarters, all to one buyer
The first 46 skids shipped in Q3 FY26. By Q1 FY27 Aeroflex sold 1,040 of them for ₹32.4 Cr, which is 22.3% of revenue. The FY27 guide of 20-22% was met in the first quarter, and management chose not to restate it.
The buyer is the Indian arm of a US-listed company. Management calls it a normal buyer-seller deal with five years of exclusivity for India, which ties Aeroflex's India skids to that buyer, not the buyer to Aeroflex. Talks with customers abroad are on, with no date.
One detail is worth holding. The average skid sold for about ₹4.99 lakh in Q3 FY26 and ₹3.11 lakh in Q1 FY27. Management says price follows the design, and the contractor's drawings set the design.
3. There is no lock on the trade: qualifying takes about a year, and Aeroflex got in that way itself
Our moat call is no moat. Winning the cooling contractor took about 10-11 months of trials and approvals, and Aeroflex crossed that same hurdle as a newcomer, in metal bellows and then in skids.
Its rivals are already at it. Management names Parker and Senior as competitors who "have also started with this business vertical". Aeroflex's cost edge is real, but it is India's edge, shared by any Indian maker, and its own estimate of its global share is about 1-1.5%.
So the pipe-fitter has a good contractor and no exclusive claim on the trade. The evidence for a lock would be a second contractor qualifying Aeroflex's own design, and that has not happened yet.
4. The FY27 plan runs on a skid line whose finish date has moved twice
The 15,000-skid line was first due in June 2026. In May it moved to the September quarter, and in July to October-November, which management put down to its machine supplier. Today the plant can make 9,000 a year. The hose line has the same shape: 20 million metres was due by March 2026 and is now due in the December quarter.
The money guides have mostly landed. The clear miss is old: FY24 was guided at 30-40% growth and delivered 18%. FY26's EBITDA margin came in at 22.6%, and the guide is about 23% for FY27 and 25% over the next few years.
The base business, without skids, grew 34% in Q1 FY27, but that was against a quarter that fell 6% on US tariffs. Over two years it is about 12% a year, below the 15-20% guided for FY27. The guide is believable on the money and loose on the calendar.
5. The plant has grown faster than the profit, and return on capital fell from 36% to 19%
FY26 revenue rose 18% to ₹442 Cr, but profit rose only 6% to ₹56 Cr, because depreciation more than doubled from ₹11 Cr to ₹26 Cr on new capacity. Free cash flow was negative in FY25 and FY26.
Fresh equity came in faster than the profit it earns. The 2023 listing, then a ₹55 Cr share issue in February 2026, took return on capital from 36% in FY22 to 19% in FY26.
The audit is clean and no promoter shares are pledged. Two things to keep an eye on: sales to a group company rose about eight-fold, putting related-party business at 5.2% of revenue, and an income-tax demand under appeal makes up most of the contingent claims.
6. What the price already assumes: about 54.5% a year, above all three of our cases
At ₹521 on 1 October, the price implies about 54.5% earnings growth a year. Our cases carry the revenue guide through the margin guide and put that growth at about 18% in the bear case, 39% in the base case and 50% in the bull case.
The multiples say the same. The price is 101.6 times trailing earnings, against a median of 50.7 since listing, a band only three years long.
What would make me wrong
- The skids are already ahead. One quarter met the full-year share guide, and the 15,000 line, once running, adds two-thirds to today's capacity.
- The base is recovering fast. 34% growth in Q1 FY27 and a tariff cut in February 2026 may mean the core does better than 15-20%.
- A second contractor. Management is in talks abroad. One named order would change the concentration story and test the moat call.
The opposite error would be to treat one quarter of skid revenue as a trend. There are three quarters of it, from one buyer.
The one question that matters
Skid capacity: 9,000 a year today, 15,000 promised for October-November 2026. The next call says whether it arrived or moved a third time.
What I'll be watching
- Does the 15,000-skid line start up by November, with no new date?
- Does the base business grow 15-20% once it laps the tariff-hit quarter?
- Is a second skid customer named, in India or abroad?
Final assessment
Aeroflex has turned a hose shop into a cooling supplier in three quarters, and the money guides mostly land. What it has not shown is a second buyer, or a line that starts up on its first date.
The full read is on the Aeroflex Industries company page.
The pipe-fitter has one big contractor and a new set of tools on order. The price is paying as if the tools are already running and the second contractor has already called.
This is a summary of what Aeroflex Industries' filings, earnings calls, annual reports and broker notes say. It is not investment advice or research.