Venus Pipes & Tubes: It holds at the pressure it rated. It leaks the moment it raises the rating
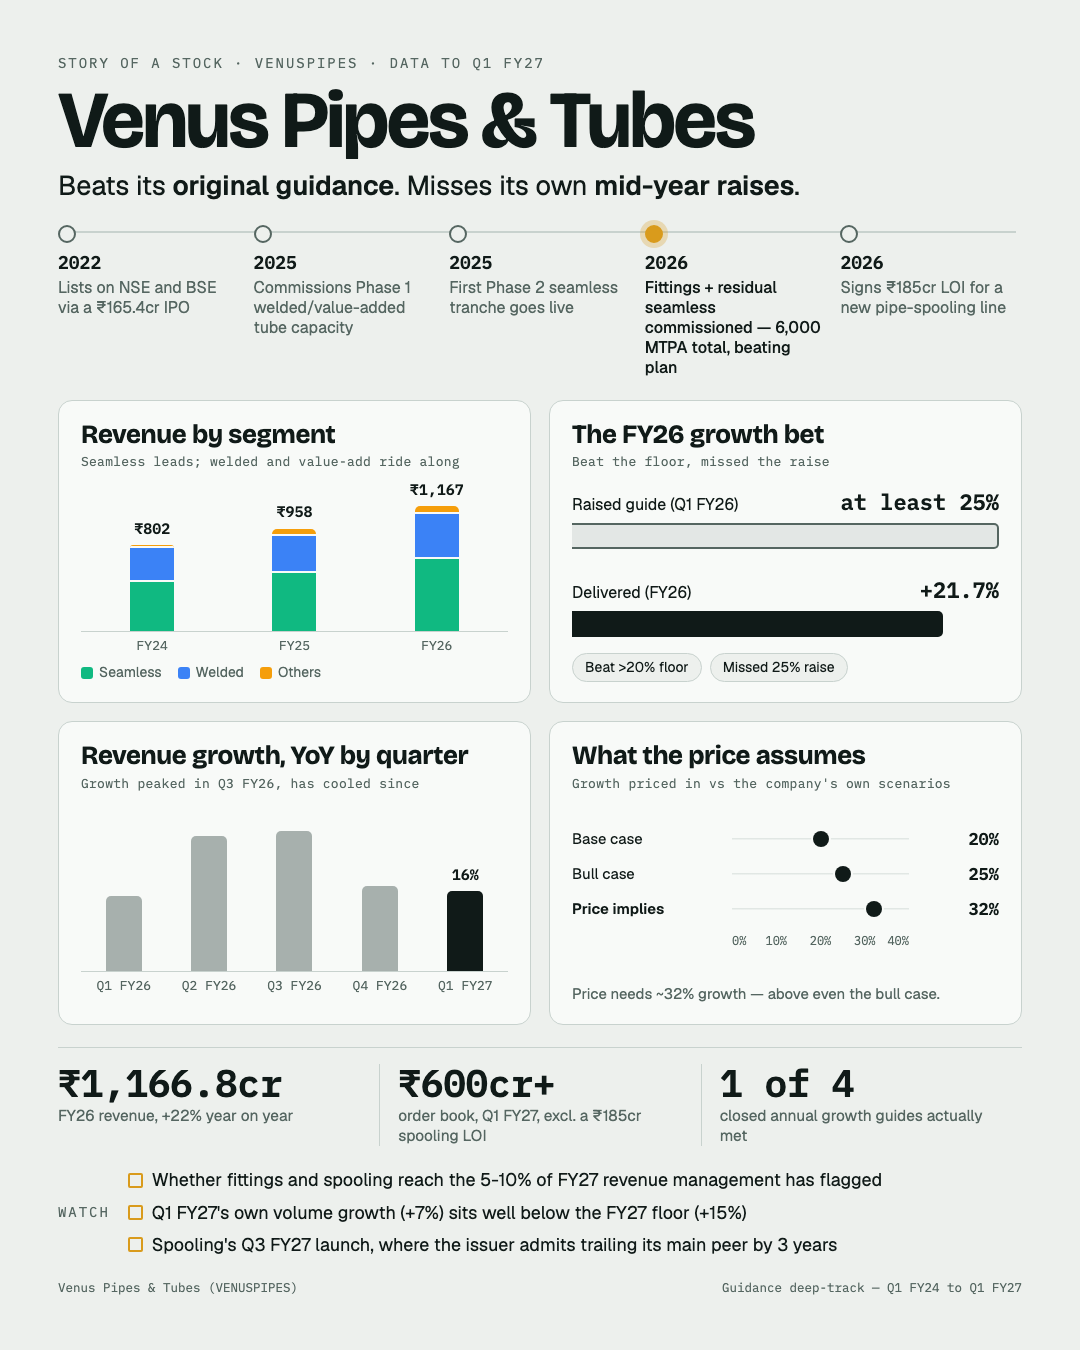
That's the whole Venus Pipes story on one page. Below is the same thing in words, built from every concall transcript and investor deck the company has published, plus nine broker notes.
A pipe is rated for a pressure.
Venus Pipes and Tubes makes stainless-steel pipes for oil refineries, power plants, and now data centres.
Every year, its management rates a growth pressure it expects the business to hold.
Every year so far, the pipe has held, at the pressure it first rated.
The trouble starts when management turns the rating up partway through the year.
The central takeaway
The original number has never broken. The upgraded number has broken twice.
The debate is no longer whether Venus can grow at 20%-plus a year. It is whether you should believe the extra few points it adds once the year is already going well.
At a glance
- FY26 revenue: Rs1,166.8 crore, up 22%. FY24 grew 45%.
- FY26 guide: more than 20% at the start of the year, raised to at least 25% mid-year. Delivered: 21.7%.
- Capacity: seamless expansion delivered 6,000 tonnes a year against a 4,800-tonne plan. Fittings capacity, promised for March 2025, arrived in May 2026.
- Order book: more than Rs600 crore, plus a separate Rs185 crore letter of intent for a new pipe-spooling line.
- The record: one of four closed annual growth guides actually met. Six slips across nine dated capacity and order commitments.
- What the price assumes: about 32% growth a year, above the company's own 25% bull case.
1. The floor has never broken
Venus guided 40-50% revenue growth for FY24. It delivered 45%.
It guided more than 20% for FY26. It delivered 21.7%.
Its Phase 2 seamless expansion was planned at 4,800 tonnes a year. It came in at 6,000.
Whatever number Venus commits to first, in the room, on the call that opens the year, it has a real record of clearing.
That is the base case. It needs no new product line and no new customer.
2. The lock covers a third of the pipe
Getting approved to supply stainless pipe for oil and gas or power projects can take years. Venus says its approvals in the Middle East are scarce enough that even large Chinese manufacturers hold few of them.
That is a genuine lock. A customer who has spent years qualifying Venus is not switching suppliers for a small discount.
But that lock only covers the export and qualified book, which broker estimates put at about a third of revenue. The larger domestic book is not approval-gated and stays open to any competitor with capital.
And the company's own named rival, Ratnamani, is bigger on stainless-pipe capacity and has a three-year head start in the one new vertical Venus is now entering.
3. The lever is a pivot from pipe to finished part
Base pipe is a commodity. Fittings, pipe spooling, and condenser tubes are not.
That is the whole logic behind the margin guide: from 16.3% delivered in FY26 toward "around 18%" by FY28-29.
Fittings capacity is now live. A signed Rs185 crore letter of intent from a data-centre customer backs the new spooling line, targeted to start commercial production in the December quarter of 2026.
Management itself, under persistent questioning on a recent call, floated doubling the business by FY29 or FY30. That number came from an analyst's own arithmetic, and management's confirmation was two words: "before that."
4. The rating cracks exactly where it gets turned up
Fittings capacity was first promised for March 2025. It slipped to the first half of FY26, then to the second half, then arrived in May 2026, three restatements after the original date.
A Rs190 crore boiler-tube order, won in early FY25 with a self-set internal target of finishing "before June 2026," was still under 60% executed five weeks before that deadline, with no update since.
And FY26's growth story repeats FY25's: management raised its own floor mid-year, then delivered short of the raised number both times.
The newest version of the same pattern is already visible. FY27's guide is a volume floor of "higher than 15%." The same quarter that repeated the floor also reported its own blended volume growth at "more than 7%."
5. What the price already assumes
Working backward from today's price, Venus needs to grow earnings at about 32% a year to justify itself.
The company's own base case is 20%. Its own bull case, the top of its own range, is 25%.
The price is not asking for the guide. It is asking for something above the best number management has put forward.
What would make me wrong
- The original guide has never missed, four years running. A company that reliably clears its own opening number has earned some benefit of the doubt on the next one.
- Capacity has landed above plan, not below it. The fittings delay was about timing, not about scope: 6,000 tonnes of seamless capacity against a 4,800-tonne promise is a real beat.
- The spooling letter of intent is signed, not aspirational. Data-centre demand for pipe spooling is a real, named order, not a hopeful mention.
- Most of the live guidance is a promise, not a fact. Of sixteen live commitments, three are backed by a signed order or committed capex, eleven rest on management's word, and two are long-range ambition surfaced under questioning.
If I am too harsh here, it is because a company that has never missed its first number deserves more patience on its second.
The one question that matters
What share of FY27 revenue actually comes from fittings and spooling?
Management has pointed to roughly 10-12% combined. Today, fittings has just started and spooling has not launched at all.
Everything about the raised guide depends on that number moving from near zero to double digits within two quarters.
What I'll be watching
- Does the spooling line start commercial production in the December 2026 quarter, or slip again?
- Does the Rs190 crore boiler-tube order actually finish, or does it join the fittings line as a repeat delay?
- Does FY27's own volume growth close the gap to the 15% floor, or does the floor quietly move instead?
Final assessment
Venus has proved it can hit the number it opens the year with.
It has not yet proved it can hit the number it gets excited about once the year is going well.
The full read, including every guidance thread and the sources behind it, is on the Venus Pipes and Tubes page.
A pipe rated for a pressure holds, until someone turns the pressure up. The higher rating is the one still waiting to be tested.
This is a summary of what Venus Pipes and Tubes' filings and nine broker notes say. It is not investment advice or research.