Sterlite Tech: One tenant signed most of the lease. The rent starts when they move in
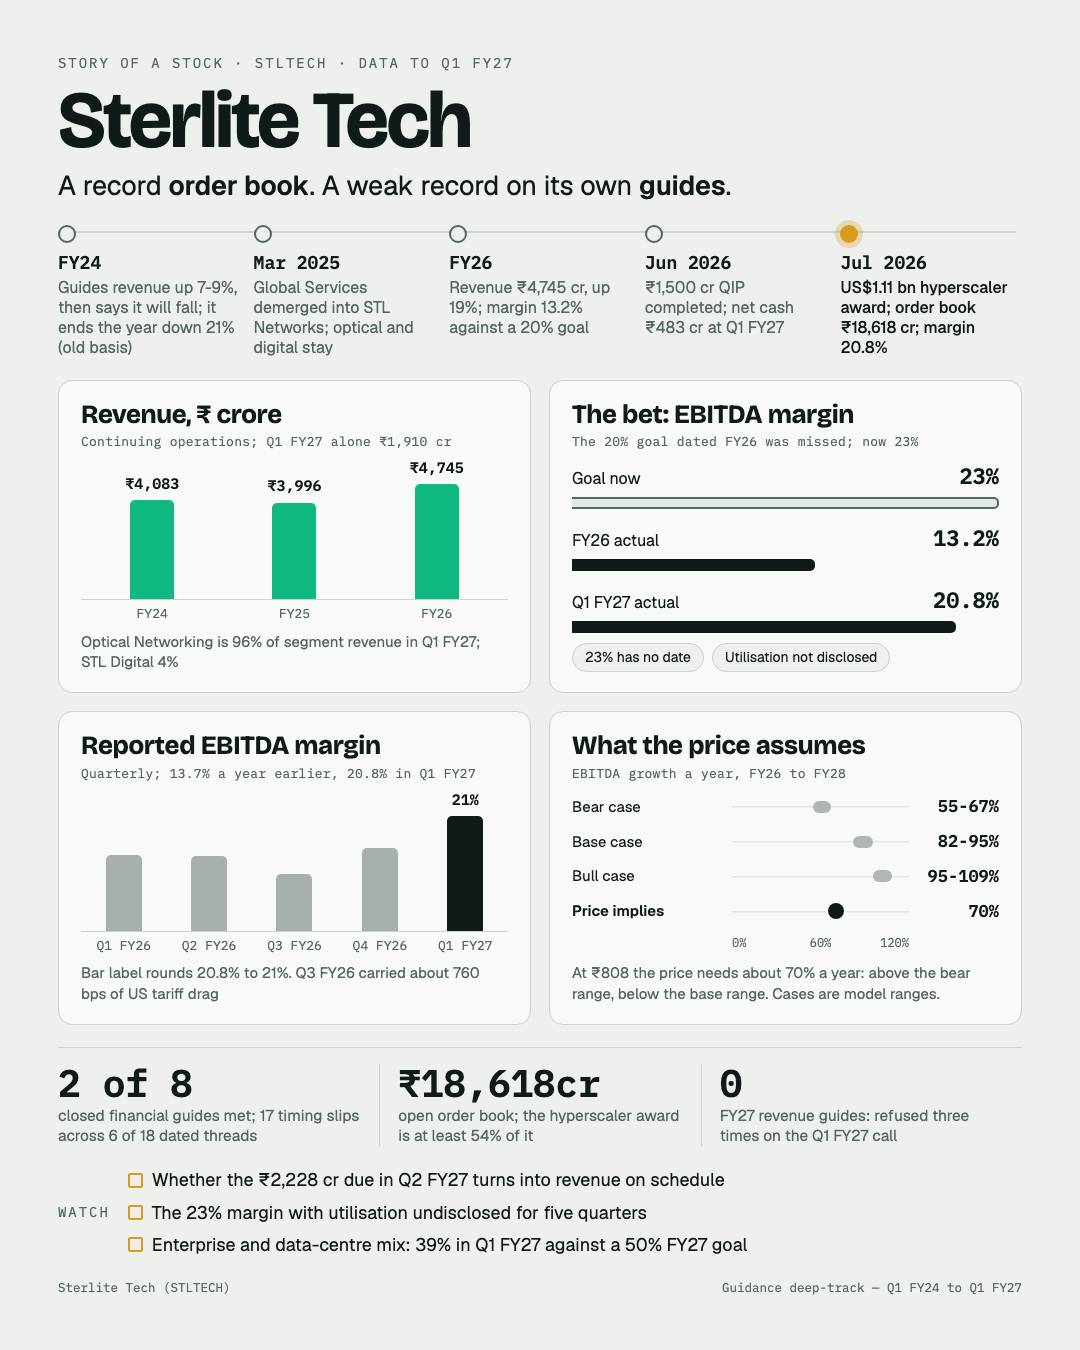
That is the whole Sterlite Tech story on one page. Below is the same story in words, built from thirteen quarters of concall transcripts, eleven investor decks and the broker notes we hold. Figures are consolidated as reported, for continuing operations after the Global Services demerger on 31 March 2025.
A building fills up when an anchor tenant signs.
Signing is not moving in. Rent only starts when the tenant is in the space.
Sterlite Tech makes optical fibre and connectivity products. In one quarter, one hyperscaler signed for most of the building.
So the story is when the rent starts. And the landlord has stopped posting the occupancy sign.
The central takeaway
The lease is real. The order book went from Rs7,309 crore to Rs18,618 crore in a single quarter.
The debate is no longer whether demand for data-centre fibre exists. It is whether the rent starts on management's schedule, from a company whose schedules have slipped.
At a glance
- The order book: Rs18,618 crore open at Q1 FY27, up from Rs7,309 crore. Only Rs2,228 crore is due for execution in Q2.
- The guide: no revenue guide, refused three times on the Q1 call. A 23% EBITDA margin, no date. A 50% data-centre and enterprise mix for FY27.
- The record: 2 of 8 closed financial guides met. 17 timing slips across 6 of 18 dated threads.
- The margin: 13.2% in FY26, 20.8% in Q1 FY27.
- What the price assumes: about 70% EBITDA growth a year for two years, against 82-95% in the base case.
1. One tenant signed most of the lease
Q1 FY27 order intake was Rs13,100 crore. All of FY26 was Rs7,687 crore.
The driver is a US$1.11 billion award from a global hyperscaler, for FY27 to FY29. That is more than Rs10,000 crore.
Against the Rs18,618 crore book, that is at least 54%. The share is my arithmetic, and it assumes the whole award sits inside the book.
One customer now shapes how visible the next three years are.
Management calls the book well diversified. The arithmetic says one lease dominates it.
2. A signed lease is not rent
Management gives no revenue guide. It said so three times on the Q1 FY27 call.
What the book gives is a schedule. Rs2,228 crore is due in Q2 FY27. The other Rs16,390 crore falls in Q3 FY27 and beyond.
One broker, CLSA, describes the award as periodic purchase orders under a capped, reciprocal-liability framework. That detail is from the broker only. No company document states it.
So the award is a framework for orders, not an order for the full amount.
Revenue was Rs1,910 crore in Q1 FY27, up 87% on a year earlier. FY24 to FY26 was Rs4,083 crore, Rs3,996 crore and Rs4,745 crore.
The move from Q1's run-rate to the book is the part nobody has guided.
3. The occupancy sign was switched off
Management's margin goal rests on one condition: factory utilisation.
The last published level was 40-50%, in Q4 FY25. Disclosure stopped from Q1 FY26. Every quarter since, management has declined to give a number.
Reported EBITDA margin was 13.2% in FY26. The 20% goal dated to FY26 was missed by about 680 basis points.
In Q1 FY27 the margin printed 20.8%, three quarters ahead of the FY27 date. In the same breath the goal was raised to 23%, with no date.
That is a real result. It is also one quarter, and the condition behind it cannot be checked.
4. The landlord's forecasts have a weak record
Two of eight closed financial guides were met. The two were segment-level: the attach rate, and STL Digital's break-even, which came three quarters late.
The six misses include the FY24 revenue guide of 7-9% growth, reversed within a quarter, and the FY26 margin goal.
On dates, 17 slips fell across 6 of 18 dated threads. The BEAD-linked US demand ramp alone was re-dated six times.
Eleven of the 18 never slipped. Five commitments were quietly dropped rather than missed, and dropped ones do not count in the 2 of 8.
The record also leaves out FY27, which has not closed. The 20% margin came early and net debt turned to net cash of Rs483 crore, after a Rs1,500 crore QIP (the figure includes QIP cash pending allocation).
Of 13 live guides, 2 are backed by an order. The other 11 are management's word (6) or aspiration (5).
5. The new tenants are still on the waiting list
Data-centre customers were 1% of revenue in FY26 and 21% in Q1 FY27. With large enterprises, the combined share is 39%. The goal for FY27 is 50%, up from 30% a quarter earlier.
The attach rate, connectivity sold alongside cable, was 22% in FY25, 15% in FY26 and 16% in Q1 FY27. The goal is above 20% from Q2 and 25% by Q4 FY27.
Capex went from a one-off Rs500 crore to Rs500 crore a year for three years. Management twice declined to say how much capacity it adds.
Each of these is a promise about the next tenants, not a fact about the current ones.
6. What the price already assumes
The share price was Rs808 on 21 September 2026, a market value of Rs41,554 crore.
Working backward from the price, EBITDA has to grow about 70% a year for two years, from FY26's 13.2% margin.
Our growth read is model work, not management guidance. It carries revenue growth through the 23% margin the company itself guides.
The bear case is 55-67% a year, the base case 82-95%, and the bull case 95-109%. The bear case holds the margin at 20%.
So the price sits above the bear range and below the base range. Our growth score is 8.0 out of 10.
The multiples sit outside their five-year ranges. EV to EBITDA is 49 times, against a five-year median near 13.
What would make me wrong
- The book converts. If Rs2,228 crore in Q2 turns into revenue on time and the award's call-offs run at pace, a weak forecasting record matters less than a full order book.
- The margin is structural. Data-centre products may simply earn more. Segment margin at Optical Networking was 21.8% in Q1 FY27, against 13.5% in FY26.
- The books are cleaner now. Net cash, a completed QIP and a hit 20% margin are things earlier years could not show.
- My moat read may be too hard. I read it as no moat: returns on capital of 3.1%, 2.4% and 6.9% in FY24 to FY26, per a broker, below my assumed cost of capital. One strong quarter does not settle that.
The opposite error would be trusting the book because it is large. A lease this size still needs the tenant to move in.
The one question that matters
Does the reported EBITDA margin hold, and reach 23%?
It was 13.2% in FY26 and 20.8% in Q1 FY27. Management wants 23%, with no date.
Everything else hangs off it: the mix, the attach rate, and the price.
What I'll be watching
- Does the Rs2,228 crore due in Q2 FY27 show up as revenue, and at what pace do the award's call-offs follow?
- Does the margin stay near 20.8% in the Q2 and Q3 prints, with utilisation still undisclosed?
- Does the data-centre and enterprise mix move from 39% toward 50%, and the attach rate toward 25% by Q4 FY27?
Final assessment
Sterlite Tech has proved the tenant signed.
It has not yet proved the schedule, and its record on schedules is the weak part.
The full read, including every guidance thread and the sources behind it, is on the Sterlite Tech page.
A lease is a promise about the future. The rent is a fact.
This is a summary of what Sterlite Tech's filings and the broker notes we hold say. It is not investment advice or research.