Netweb Technologies: It always quotes a year. It keeps handing over the keys early.
Pranav Yadav · · 7 min read
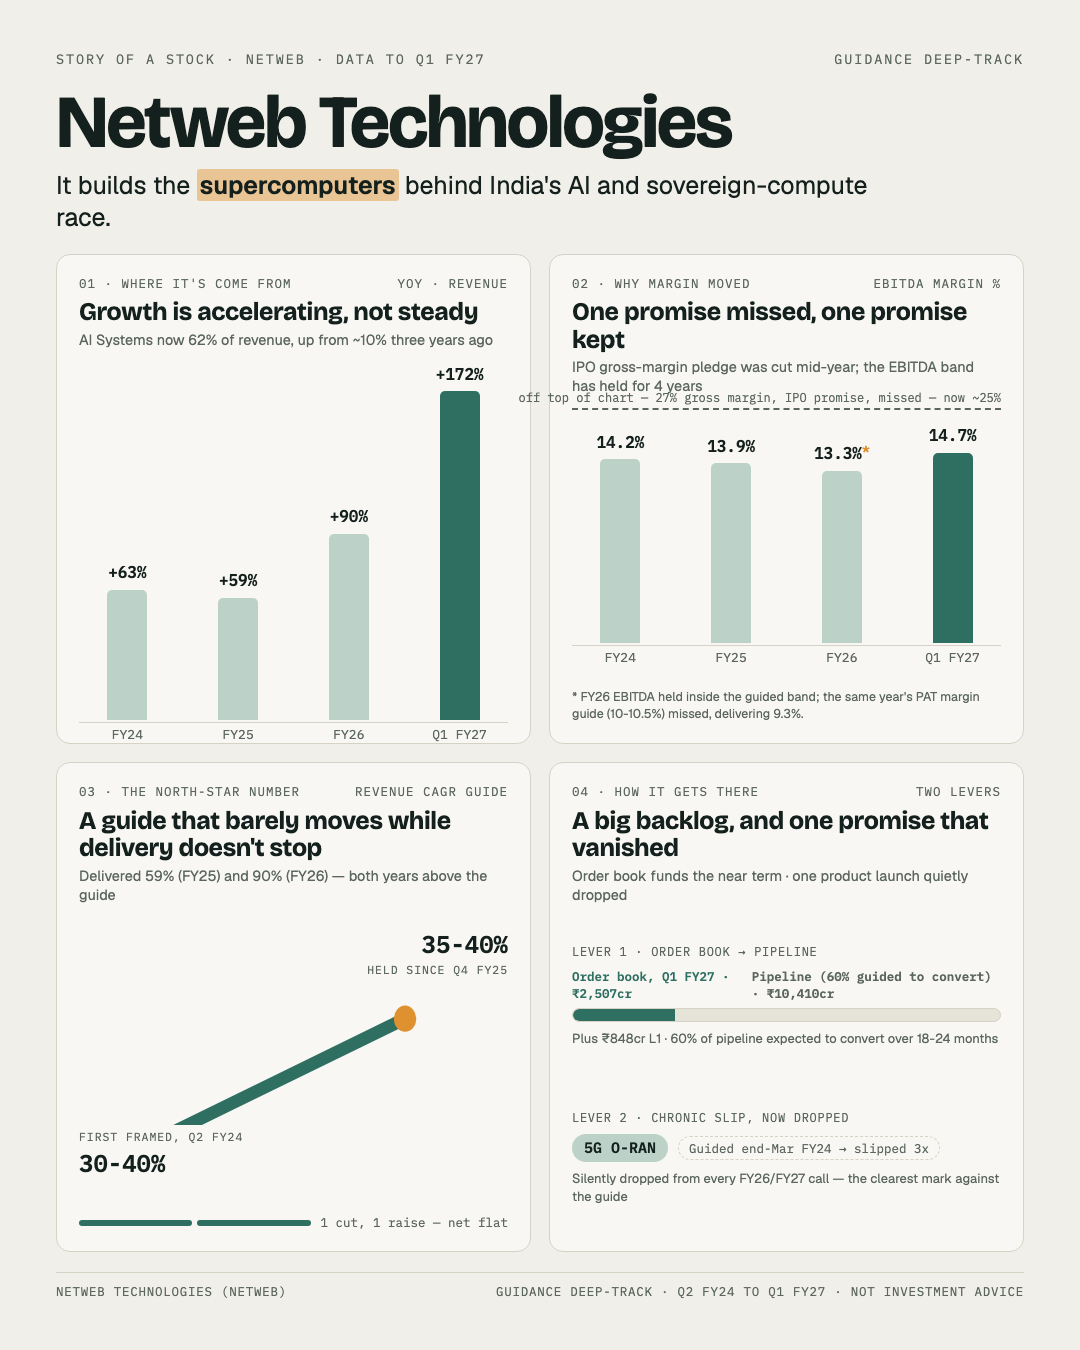
The whole story on one page. Below is the same thing in words, built from every transcript and deck the company has published since its IPO, plus the broker notes covering it.
Ask a contractor how long the build will take.
You'll hear the same answer this year as you heard three years ago, even though the crew has gotten faster and the last four houses all went up early. That's not humility. That's a number that stopped tracking the work.
Netweb Technologies builds the supercomputers, AI systems and private-cloud hardware behind India's compute build-out. It has quoted a "30-40% CAGR" for its business since its first call after listing, cut that once, then raised it back to "35-40%" a year and a half ago. It has delivered 59%, then 90%, then 172% year-on-year in the quarter after that.
The quote hasn't caught up. The keys keep arriving early.
The central takeaway
The debate is no longer whether Netweb is growing. The growth is not in question — it shows up in the order book, the AI-systems mix, and every printed revenue line.
The debate is whether a guide that hasn't tracked four years of delivery is still a useful number, and what it means that the one specific product promise the company made — not a growth band, an actual launch date — quietly disappeared instead of being marked missed.
At a glance
- Growth has outrun the guide every single year. FY24 +63%, FY25 +59%, FY26 +90%, Q1 FY27 +172% year-on-year — against a CAGR guide that moved from "30-40%" to "30-35%" and back to "35-40%," where it has sat since Q4 FY25.
- AI Systems went from a side business to the business. About 10% of revenue in the first half of FY24. 62% of revenue in Q1 FY27, up 484% year-on-year that quarter alone.
- The EBITDA promise has held for four straight years. Guided 13-14% every year since FY24; delivered 14.2%, 13.9%, 13.3% and now 14.7% in Q1 FY27 — running ahead of its own band.
- The gross-margin promise did not hold. Management committed to "around 27%, as we committed during the IPO." Two quarters later it cut that to 25-26%. Nine months into FY24 it was 25.4%.
- The backlog is real and growing. Order book of Rs2,507 crore plus Rs848 crore already at the final negotiation (L1) stage, against a Rs10,410 crore pipeline the company guides 60% of to convert over the next 18-24 months.
- One named product promise simply vanished. A 5G O-RAN product, guided for launch by the end of FY24, slipped three times across four quarters — then was never mentioned again in any FY26 or FY27 call.
- The moat read is thin. One weak patent source, no switching-cost or scale advantage against Dell, HPE, IBM or Lenovo — all named on Netweb's own competitor slide — and a listed record too short to test any of it properly.
Two promises, two outcomes
Netweb made two margin commitments around its 2023 listing. One held. One didn't.
The EBITDA band — 13-14% — has been reaffirmed at nearly every call since, cut once from an initial "14-15%," then held. Four years of prints have landed inside or above it, including 14.7% in the most recent quarter.
The gross-margin pledge — "around 27%, as we committed during the IPO" — did not survive two quarters. It was cut to 25-26% within six months, and delivered 25.4% for the year it was made for. "Credible on margins" depends on which margin line you're asking about — the same pattern repeats one level down, where the FY26 PAT margin guide (10-10.5%) came in at 9.3%, later reframed against a looser 9-10% band that wasn't the number originally set.
The backlog is the site plan
None of this growth is unbacked. As of the June quarter, Netweb carried a Rs2,507 crore order book, another Rs848 crore at the final-negotiation stage, and a Rs10,410 crore pipeline it guides 60% of to convert within 18-24 months — plus a roughly Rs2,184 crore strategic order secured in FY26, tranches of which management says ran ahead of schedule.
That's the more useful lens on Netweb right now: not the CAGR band, which has stopped moving, but the size and conversion pace of the pipeline behind it.
The wall that never went up
In the second half of FY24, Netweb told investors a 5G O-RAN product would launch by the end of March. It didn't. The company called it "under development" the following quarter, pushed it to roughly the fourth quarter of FY25, then pushed it again by one to two more quarters.
After that: nothing. No mention in any transcript from FY26 or FY27, across five quarters of calls. Every other named product commitment in this record — an ARM-based server line, a roadmap of NVIDIA GPU-based systems, a new manufacturing facility — eventually shipped, on time or with a modest, disclosed delay. This is the one that didn't, and instead of being marked missed on a later call, it was simply never brought up again. That gap, between "walked back" and "silently dropped," is the clearest data point on how this management handles a promise that isn't working out.
No one else is building this exact house
Netweb names IBM, Dell, HPE, Lenovo and ATOS as competitors on its own investor-deck slide — and by revenue, it is smaller than all of them. Repeat-customer revenue runs as high as 90%+ in some quarters, but management's own explanation is refresh-cycle economics, not customer lock-in. The clearest intangible asset on record is a small, recent set of design patents, with no stated runway and no claim they protect a specific revenue line.
None of that makes Netweb a bad business. Its edge, so far, is execution speed and relationship depth, not a structural barrier a better-funded rival couldn't contest — and it's been listed under three years with no downturn in that window, so there's no way yet to test whether returns hold up when the cycle turns.
What the price already assumes
A reverse read of the price implies growth above even the bull case built from Netweb's own guided numbers, and the shares trade at several times the industry's median multiple. Both reads point the same direction.
What would make me wrong
- The pipeline is real — Rs10,410 crore, 60% guided to convert. If that holds, the gap between guide and delivery could keep widening, and today's price could still be earned into over a longer horizon than a reverse-DCF captures.
- The EBITDA band has a genuine four-year record. Margin credibility, on that one line, hasn't been an issue — only revenue-guide precision and one product promise have.
- A reverse-DCF is backward-looking; a young company compounding off a national infrastructure wave can outrun it for years. Dismissing the growth story for a conservative guide would have been wrong every year since listing.
The one question that matters
Does AI Systems revenue keep climbing past 62% of the mix as the Rs10,410 crore pipeline converts, or does it plateau once the current strategic order is worked through and the business reverts to its slower organic pace?
What I'll be watching
- Whether the FY27-28 EBITDA band (13-14%) still holds now that the adjacent PAT margin line has already missed once.
- Whether the export-share and segment-mix promises, both already cut or drifting, settle at a new number.
- Whether a second promise gets quietly dropped the way 5G O-RAN was, rather than walked back on a call.
Final assessment
Netweb's delivered growth has been real and understated by its own guide every year since listing. Its EBITDA discipline has a genuine four-year record. Its gross-margin pledge and one product launch did not survive contact with the business — and the second one simply went quiet instead of being addressed.
The read here isn't that the guide is dishonest. It's that a standing band this far behind delivery, sitting next to one abandoned promise, says more about how carefully to read every other number this company puts on a slide than the headline growth rate does.
Full record on the company page.
The contractor keeps quoting a year. The keys keep arriving early. At some point a reader has to decide whether that's a company being careful with a number it can't fully control — or one that would rather you not ask why the quote never changes.
This is a summary of filings and disclosures, not investment advice.