HFCL: The bricklayer bought the brickworks. The second kiln keeps opening late
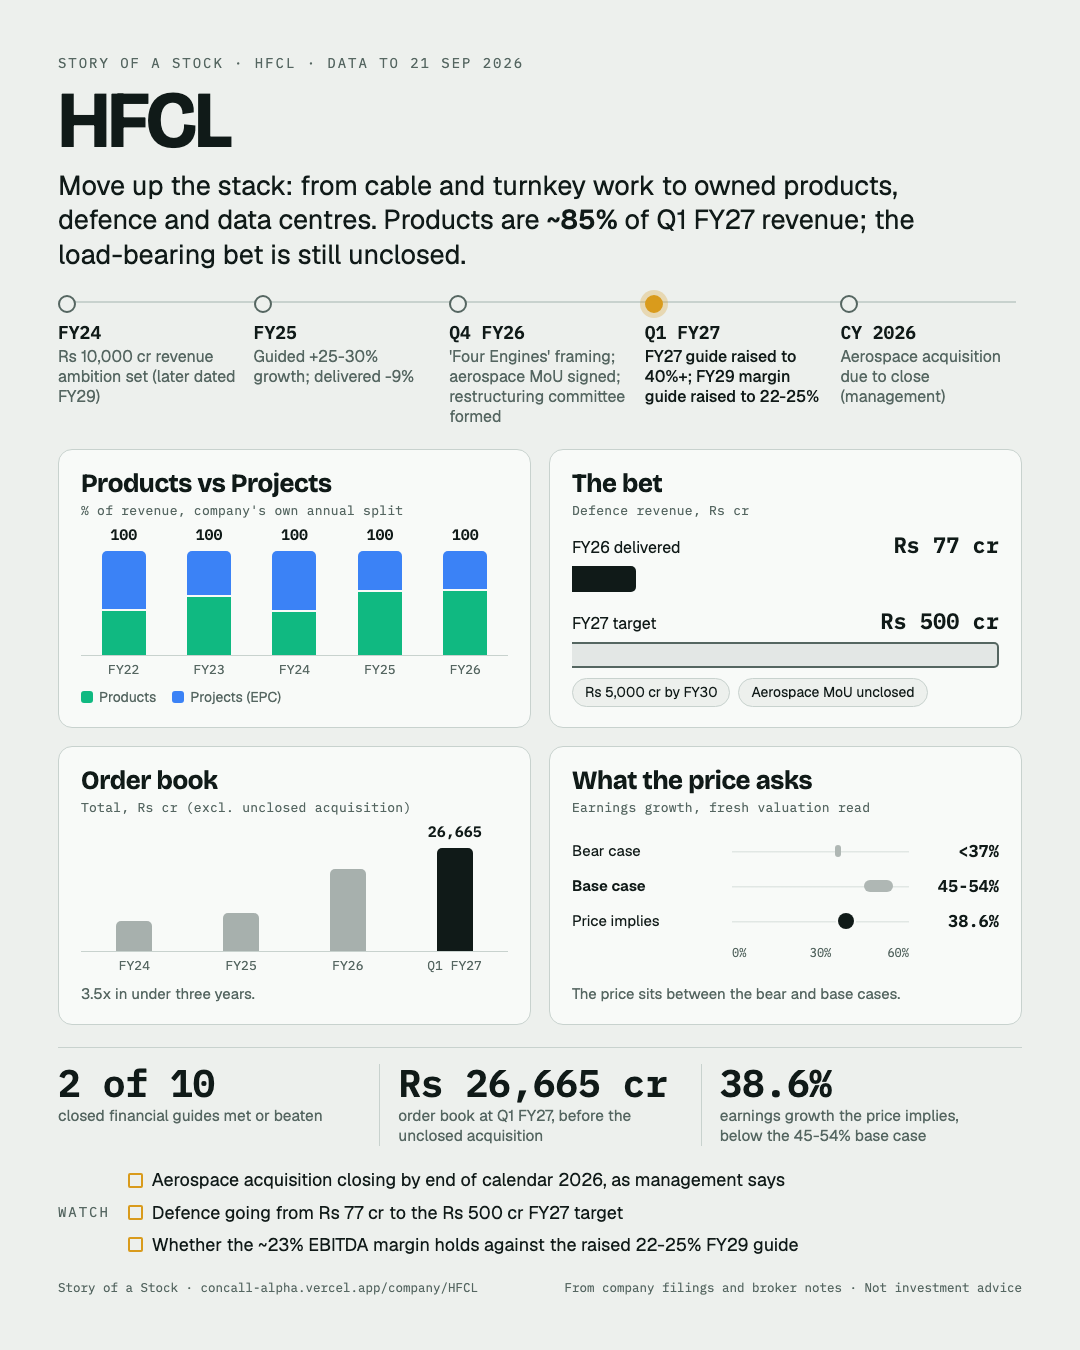
That is the whole HFCL story on one page. Below is the same story in words, built from thirteen quarters of concall transcripts, fourteen investor decks and the broker notes we hold. Figures are consolidated as reported.
A bricklayer lays bricks for other people. He is paid per job, and the job ends.
A brickworks sells bricks to anyone, and the kiln keeps running.
HFCL spent years as the bricklayer, building telecom networks for others. It is now trying to become the brickworks: making the fibre, the cable and the equipment itself.
So the story is the kilns. How many are lit, and how many are still promised.
The central takeaway
The move is real. Products were 43% of revenue in FY22 and 62% in FY26, and about 85% in Q1 FY27 alone.
The debate is no longer whether HFCL can make things. It is whether the second and third kilns, defence and data centres, light on the dates management gives.
At a glance
- The mix: products 62% of FY26 revenue, projects 38%. Q1 FY27 alone was about 85% products.
- The order book: Rs26,665 crore at Q1 FY27, up from Rs7,685 crore at FY24. It excludes an aerospace deal that has not closed.
- The record: 2 of 10 closed financial guides met or beaten. 30 date slips across 12 of 17 dated threads.
- The raise: FY27 growth guided at 20-25% in May, then 40%+ in July after a Rs1,915 crore first quarter.
- The margin: EBITDA margin was 23.25% in Q1 FY27, including other income. The FY29 goal was raised to 22-25% from 20-21%.
- The price: it implies about 38.6% earnings growth, against under 37% in our bear case and 45-54% in the base case.
1. The first kiln is lit, and the bricks are selling
The fibre kiln is the banked part of the story.
Optical fibre capacity doubled to 28 million fibre-kilometres. Cable capacity is 34 million, going to about 43 million. Fibre expansion is due by December 2026.
The order book went from Rs9,967 crore at FY25 to Rs21,206 crore at FY26 and Rs26,665 crore at Q1 FY27.
About 56% of Q1 FY27 revenue was exported. Private customers were about 92%.
HFCL now describes itself as four engines: optical fibre, cable and connectivity; defence; telecom equipment; and EPC. It reports revenue for only two groups, products and projects, so we cannot draw the four-engine mix.
Two of its calls also give different product shares for the same quarter, 66% and 85%. We use its own annual chart and treat the quarter figures as approximate.
This part of the case rests on signed orders and plants that exist. That is how far the evidence goes.
2. A brickworks pays off in margin per brick
Margin is where the brickworks pays off.
EBITDA margin was 4.93% in Q1 FY26, 18.47% in Q4 FY26 and 23.25% in Q1 FY27. The Q1 figure includes other income.
Management now says 22-25% by FY29. Two months earlier the same slide said 20-21%.
Some of the gain is mix. Products carry more margin than projects. The EPC book still has a loss-making Army warranty tail, which management says is improving.
Running margins ahead of a goal is a good sign. It is one quarter.
3. The second kiln keeps opening late
Here the record matters.
For FY25 the company guided revenue growth of 25-30%. The managing director confirmed it when asked. Revenue from operations fell 9.0%. Management later called it an aspiration.
Across ten closed financial guides, two were met. Thirty dates moved across twelve of seventeen dated threads. One programme, electronic fuzes, slipped seven times.
A debt-to-equity cap of 0.30 was breached at 0.35.
Our scorer calls the record low trust. It is a record about timing as much as size.
That does not mean the fibre kiln is late. It means the new kilns have a history to overcome.
4. The neighbour's yard has no deed yet
Defence is the next kiln. Revenue was Rs77 crore in FY26. The goal is about Rs500 crore in FY27 and Rs5,000 crore by FY30.
Most of the jump depends on buying an aerospace business. The MoU was signed on 25 March 2026. Management says completion will come within calendar 2026.
About Rs2,000 crore of export orders come with it. They are not in the Rs26,665 crore.
A separate board committee is also studying a possible restructuring, including an EPC demerger. No decision has been announced.
Of thirty live items in the guidance book, eight are backed by orders and eighteen are asserted. Four are aspirations.
5. What the price already assumes
We solve for the earnings growth the price needs. It comes to about 38.6% a year.
That sits above our bear case of under 37% and below the base case of 45-54%. Those cases bridge the revenue guide through the margin guide, using EBITDA growth as the earnings proxy.
So the price asks for more than the bear case and less than the base case. It asks for that from a company with a low-trust delivery record.
Broker estimates put FY26 return on capital employed at 7.3% to 9.0%. The moat is narrow and weak on returns, with one real edge: an exemption from EU anti-dumping duty on cable.
What would make me wrong
- The kilns are simply on time now. The Q1 FY27 quarter beat its own margin goal. If the next two quarters hold 22%+, the record above is old news.
- The aerospace deal closes early. Rs2,000 crore of orders would join the book and the defence ladder becomes far less of a stretch.
- The base case is too high. A 45-54% earnings path needs revenue growth of 32-35% a year for three years. If FY27's 40%+ is the peak year, that is harder than it looks.
- The labels matter more than I think. Management often declines to call its numbers guidance. I scored them anyway, and a reader who does not may weigh the record less.
The opposite mistake is trusting the raise because one quarter was strong.
The one question that matters
Can defence go from Rs77 crore to Rs500 crore in a year?
It is the cleanest test. It needs the acquisition, and the acquisition has not closed.
What I'll be watching
- Does the aerospace acquisition close before the end of calendar 2026?
- Does defence revenue show up in the next two quarters?
- Does the margin stay near 23% once other income is stripped out?
Final assessment
HFCL has built the brickworks. It has not yet shown it can open the next kiln on the date it names.
The price sits between the bear and base cases. The gap between them is the next kiln.
Read the full analysis on the HFCL company page.
A brickworks is judged by whether the kiln is hot on the day it said.
This is a summary of company filings and broker notes, not investment advice.