E2E Networks: The hotel is adding a wing as big as itself. Its guests can check out any month
Pranav Yadav · · 7 min read
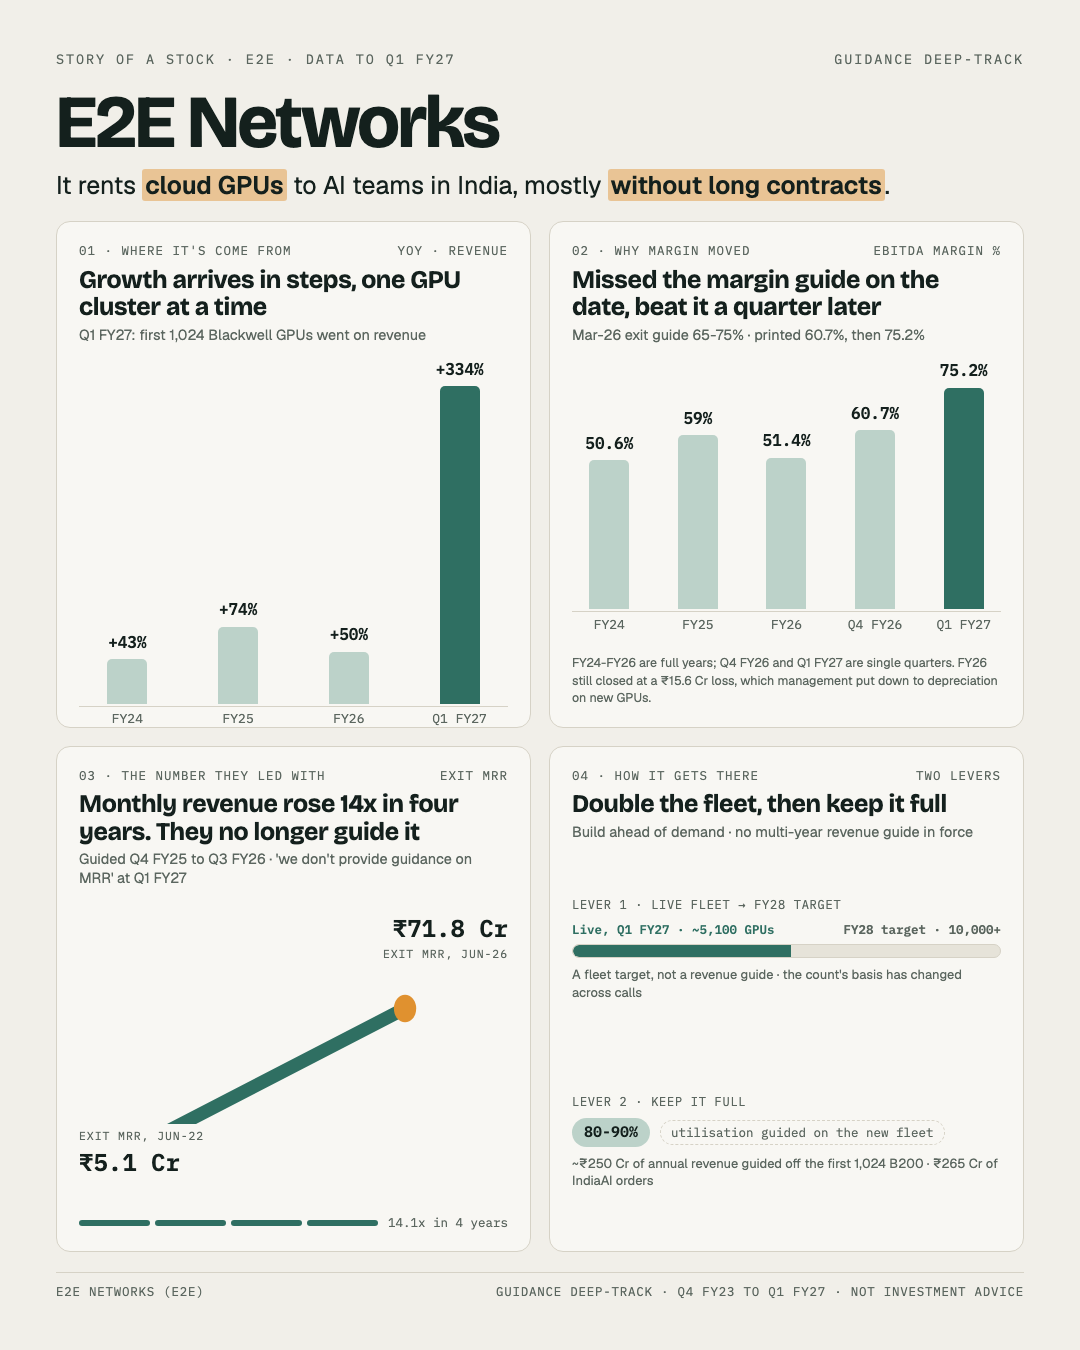
That's the E2E Networks story on one page. Below is the same thing in words, built from every earnings call transcript and investor deck the company published from Q4 FY23 to Q1 FY27.
A hotel that rents its rooms by the night lives or dies on occupancy.
E2E Networks rents GPUs, the chips AI teams use to train and run their models, out of its own data centres in India. For most of its life it has rented them the way a hotel rents rooms. Guests pay for the nights they stay and can leave when they like. The company has called this "contract-less computing" since 2009.
Now the hotel is building a new wing as big as the building it already has. About 5,100 GPUs are live today, and the target is 10,000-plus by FY28. A new wing costs money before the first guest checks in, and that is where FY26's ₹15.6 Cr loss came from.
The central takeaway
The debate is no longer whether E2E can grow. Revenue rose 43%, 74% and 50% in the last three years, and 334% year-on-year in the latest quarter.
It is whether a wing that doubles the hotel fills up at the rates management wants, 80-90% utilisation, when most guests can still check out any month.
On the record, management is credible on what it chooses to guide. The catch is how little it now chooses to guide.
At a glance
- Track record: 4 of 6 closed financial guides met or beaten, and 6 timing slips across 19 dated commitments. One multi-year growth frame was walked back.
- FY26: revenue ₹245.6 Cr, 1.50x FY25, at the bottom edge of the 1.5-1.7x guide. Exit monthly revenue ₹37.4 Cr, inside the ₹35-40 Cr guide. The margin guide missed, and the year closed at a ₹15.6 Cr loss.
- Q1 FY27: revenue ₹156.8 Cr, up 334% year-on-year, at a 75.2% EBITDA margin.
- The plan: about 5,100 live GPUs to 10,000-plus by FY28, held at 80-90% utilisation. About ₹250 Cr of annual revenue guided from the first 1,024 Blackwell GPUs, and ₹265 Cr of IndiaAI Mission orders.
- The lock: a narrow moat, rated weak. One mechanism survives our review, the depth of its TIR platform inside customers' workflows.
- What the price assumes: above 100% earnings growth a year, against a base case of about 69% and a bull case of about 91%.
Where this lives on the portal: the E2E Networks guidance page.
1. It met most of the guides it gave, then it stopped giving them
The FY26 guide was revenue of 1.5-1.7x FY25. It delivered 1.50x, at the floor. The exit monthly revenue guide for March 2026 was ₹35-40 Cr, and it landed at ₹37.4 Cr. Overseas customers were guided to 25-30% of GPU deployment, and that was met too.
Two guides missed, both on profit. The exit-month EBITDA margin was guided at 65-75% for March 2026 and printed 60.7%. A medium-term PAT margin of 15-20% met a FY26 loss.
What changed more than the hit rate is the amount of guidance. Every call in the window carries four to nine explicit refusals. A medium-term frame of 30-40% growth, raised to 40-50%, was disowned at Q1 FY25 as "the interpretation of the people asking the question". At Q1 FY27 the company said it doesn't provide guidance on monthly revenue at all, the number it had led with for a year.
The record is good on what it covers. It covers less each quarter.
2. Guests can check out any month, so the lock is thin
Most guests in this hotel have no lease. E2E's own pitch for its Jarvislabs platform is "pay only for the minutes you compute, with no commitments or lock-in". That is good for winning customers and weak as a moat.
Some customers now want one- to three-year terms for the newest GPUs. Management says it hasn't decided what share of the fleet to put on them, so I treat it as a direction, not a lock.
The one mechanism that holds up is TIR, the platform customers use to build, tune and deploy models on E2E's GPUs. Leaving means rebuilding that workflow elsewhere. The competitors E2E names in its own filings are the global hyperscalers, AWS, Azure and Google Cloud. It names no Indian GPU-cloud rival at all, so I can't say how the lock holds against a local one.
3. The whole plan is to double the rooms and keep them full
The first 1,024 Blackwell GPUs went live in Q1 FY27. Another 1,024 are expected within a couple of months. Management guides about ₹250 Cr of annual revenue from the first cluster, and says it wants 80-90% utilisation and an EBITDA margin of about 70% at scale.
The government is the anchor guest. E2E holds ₹265 Cr of IndiaAI Mission orders, and government business was 35-40% of Q4 FY26 revenue. In Q1 FY27 that share fell to about 20-21%, so the wing cannot fill on one tenant.
Every live guide rests on this lever: more rooms, full enough, at close to today's rate.
4. The record slipped on margin, and on how the rooms are counted
The March 2026 margin guide missed on the date and was beaten a quarter later, at 75.2% in Q1 FY27. Management calls that level sustainable. It is one quarter against a full year that closed at 51.4%, so I hold it as a print, not a pattern.
The fleet count is the harder problem. On the Q4 FY26 call, 3,900 was described as "CPU, GPU, storage, all capacities put together". The Q4 FY26 deck said about 5,050. The Q1 FY27 deck put 3,900 and 5,100 on one chart titled GPU trajectory, and restated FY25 from about 3,700 to 1,900 with no note. I use the one figure the CFO defined on the record, "nearly 5,100 is the current capacity, which is live on our platform today".
A hotel that counts its rooms three ways makes occupancy hard to check. That is the number the whole plan rests on.
5. What the price already assumes
E2E's market value is about ₹12,333 Cr. Our base case needs earnings growth of about 69% a year. The bull case needs about 91%.
Working backward from today's price, the model cannot find a growth rate that justifies it, even at 100% a year. The implied rate sits above 100%.
That rests on a thin earnings base, since the last full year was a loss. It still means the price is asking for more than the best case the guides support.
What would make me wrong
- The margin may be real. If 75.2% holds on a doubled fleet at 80-90% utilisation, earnings grow much faster than revenue, which is what the base case already assumes.
- The hit rate is good. 4 of 6 closed financial guides met, and 0.32 timing slips per dated commitment, is a company that mostly does what it says.
- Government demand sets a floor. ₹265 Cr of IndiaAI orders is booked business, not a hope.
- Growth has never been slow. The weakest of the last three years was 43%.
If I'm too cautious here, it is because a company that stops guiding the number it was proudest of deserves a closer look, not a harsher one.
The one question that matters
What is utilisation on the fleet at the end of FY27, counted on GPUs alone?
Today the figure management gives is close to 80%, on a base that mixes CPUs, GPUs and storage. It wants 80-90% on a fleet twice the size.
What I'll be watching
- Does the second 1,024-GPU Blackwell cluster go live on time, or slip the way the first did?
- Does the 75.2% EBITDA margin hold for two more quarters?
- Does the company report one GPU count, on one basis, every quarter?
Final assessment
E2E Networks has grown fast and mostly kept the promises it chose to make.
It is now making fewer of them, while it builds a wing that doubles the hotel.
The full read, including every guidance thread and the sources behind it, is on the E2E Networks page.
A hotel with no long leases lives on occupancy. E2E is doubling its rooms, and the next four quarters show whether the guests stay.
This is a summary of what E2E Networks' filings and earnings calls say. It is not investment advice or research.