Aimtron Electronics: The bridge has one span still in the air
Pranav Yadav · · 6 min read
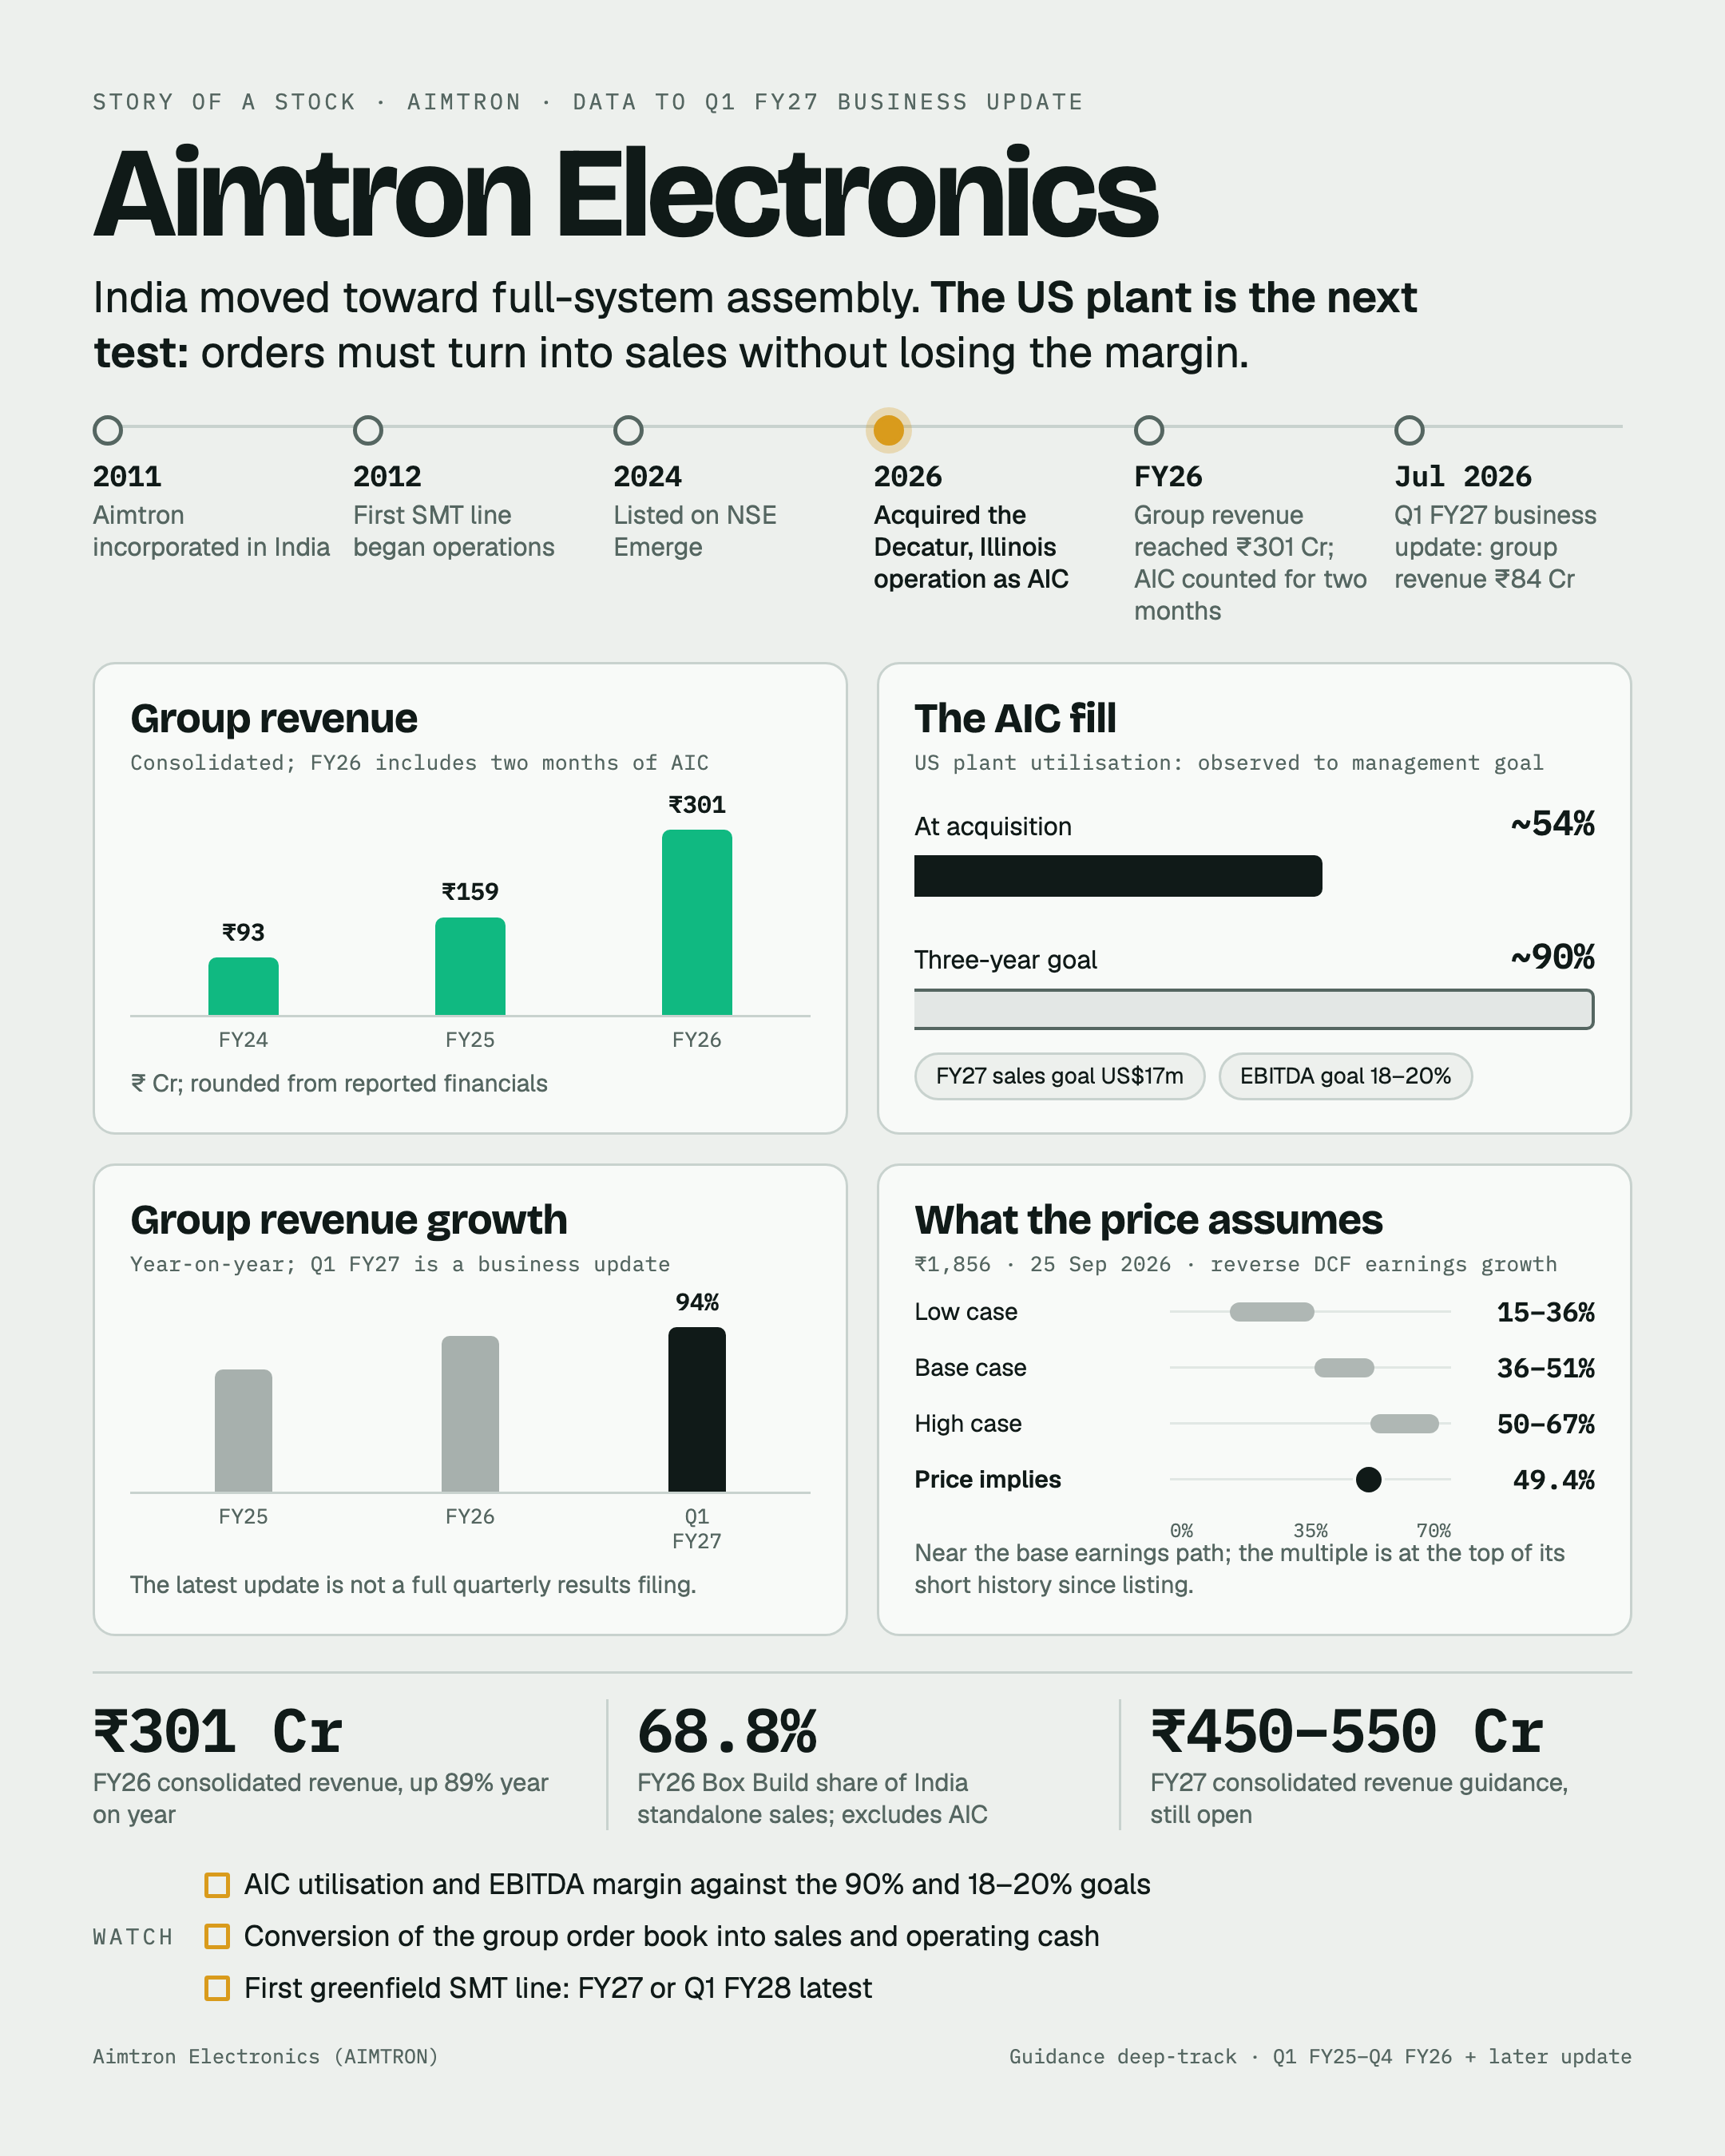
That is the Aimtron story on one page. Below is the same bridge in words, built from the company's calls, investor presentations, annual-report checks and the later business update.
Aimtron makes electronics, from populated circuit boards to complete systems. It now has an acquired Illinois plant alongside its Indian factories. The group wants to move from ₹301 Cr of FY26 revenue toward ₹1,000 Cr, with no firm date.
The India business has changed its mix and delivered growth. The US span has orders and a running factory, but its planned use and margins remain to be delivered.
The central takeaway
I can see the Indian footing in reported sales. I cannot yet treat the US ramp as delivered earnings. FY27 tests whether the two sides carry the same load.
The debate is whether the acquired plant converts orders into sales and lifts its margin while India keeps growing. The price asks for a strong earnings path despite AIC's short record inside this group.
At a glance
- The base: FY26 consolidated revenue was ₹301 Cr, up 89% year on year. AIC, the acquired US operation, contributed only two months to that year.
- The India mix: Box Build was 68.8% of FY26 India standalone revenue, PCBA 28.6% and ODM 2.6%. These are not group revenue shares.
- The guide: management's FY27 consolidated revenue range is ₹450–550 Cr. Its separate, rolling ambition is 40–50% annual growth over three to five years.
- The US leg: AIC's FY27 sales goal is about US$17 million. Management wants utilisation to rise from about 54% toward 90% over roughly three years and EBITDA margin from about 11% toward 18–20%.
- The record: one of one closed financial guides was met, too small a sample for a credibility verdict. Timing had two slips across 17 dated threads.
- The latest signal: a July business update put Q1 FY27 group revenue at ₹84 Cr, up 94% year on year. It was not a full quarterly results filing.
Where this lives on the portal: the Aimtron Electronics guidance page.
1. India built the first span with full-system assembly
Group revenue rose from about ₹93 Cr in FY24 to ₹159 Cr in FY25 and ₹301 Cr in FY26, using rounded financials. The issuer's precise FY26 figure is ₹301.16 Cr. It cleared guidance above ₹270–280 Cr. FY25 growth of about 70% also beat the standing 40–50% frame.
The mix is a different measurement. The FY26 presentation labels Box Build at 68.8% of India standalone sales. Full-system assembly can mean more work per customer, but product margins are undisclosed. That mix cannot establish a group profit estimate.
FY26 group revenue includes AIC for two months; the India mix excludes it. The bridge to the larger group target needs a separate US account.
2. The acquired US factory has orders, but its margin is still a goal
International Control Services in Decatur became AIC in 2026. It contributed about US$1.6 million over two FY26 months. This is a running operation.
The FY26 presentation puts AIC's March order book at US$7.2 million and quotation pipeline at US$49.3 million. An order needs execution; a quotation is not booked work. The FY27 sales goal of about US$17 million tests conversion.
The plan moves utilisation from about 54% at acquisition toward 90% over three years. It aims to lift AIC's EBITDA margin from roughly 11% to 18–20% later in FY27. Group guidance remains 20–22%. AIC could add sales while the margin span lags.
3. The FY27 guide needs both factories to carry the load
Management guides ₹450–550 Cr of FY27 group revenue, helped by a full AIC year and India growth. The ₹1,000 Cr goal is undated. Its 40–50% annual growth frame spans three to five years, separate from the one-year rupee range.
The July business update reported ₹84 Cr of Q1 FY27 group revenue against about ₹43 Cr a year earlier, up 94%, and combined unexecuted orders of about ₹604 Cr. It did not give AIC's new utilisation or a full cash-flow statement.
India has nine existing SMT lines and six planned at the Vadodara greenfield site. The first new line's timing moved to FY27 or Q1 FY28 latest. Planned lines are not installed capacity.
4. Cash and dates are the load test
Only one financial guide closed in this window, and it was met. Seventeen dated operational threads had two slips, including the first greenfield line and a certification. Timing is reasonably reliable; the financial sample is too small to grade.
The Quality substrate shows operating cash flow of negative ₹19 Cr in FY25 and negative ₹40 Cr in FY26 as profit rose. FY26 receivables reached ₹135 Cr and inventory ₹103 Cr. The acquisition affects comparisons, but the next test includes collecting cash from booked revenue.
India's order execution, AIC's margin and utilisation, and greenfield commissioning run on different clocks. A strong group revenue print can hide a slow one.
5. What the price already assumes
At ₹1,856 on 25 September, the reverse DCF implies about 49.4% near-term earnings growth on its EBITDA-based scenario ladder. The model's base earnings band is 36–51%; the high band is 50–67%, and the low band 15–36%. The implied growth sits inside the base band, close to its upper edge. These are model ranges, not management guides.
The valuation tension is in the multiple. The P/E was 83.2 times, at the top of the stock's own short history since its 2024 listing. EV/EBITDA was also at its short-history maximum. The no-moat assessment provides no evidenced durable premium, and the guidance credibility verdict is not assessable yet. A price can imply a plausible operating path and still leave little room for that path to arrive late.
What would make me wrong
- The US conversion may be quicker. AIC has a booked order base, and a full year of consolidation can reveal operating leverage that two months of FY26 could not.
- The India base may keep surprising. FY25 and FY26 growth beat the standing frame, and the latest group revenue update is strong.
- Cash may catch up as orders ship. Receivables and inventory can build ahead of execution. A later conversion into cash would change the reading of the two negative cash-flow years.
The opposite error is to count AIC's quotation pipeline as revenue, or the greenfield's planned lines as working capacity. Either would put weight on a span before it is finished.
The one question that matters
Can AIC move from about 54% utilisation toward 90% while lifting EBITDA margin from about 11% toward 18–20%? The sales goal needs both the factory and the margin to work. The company has not yet reported enough post-acquisition operating history to settle that question.
What I'll be watching
- Does the next filing break out AIC sales, utilisation and margin against the FY27 goals?
- Does the combined order book become reported sales and positive operating cash flow?
- Does the first greenfield SMT line start by FY27 or Q1 FY28, the widened timing range?
Final assessment
The India side of the bridge has reported growth and a clear shift toward complete assemblies. The US side has a real plant and real orders, with the utilisation and margin crossing still ahead. The share price is already measuring the finished crossing.
The full record is on the Aimtron Electronics company page. The next filing needs to show which part of the bridge is carrying the load.
This is a summary of what Aimtron Electronics's filings and our guidance and valuation records say. It is not investment advice or research.